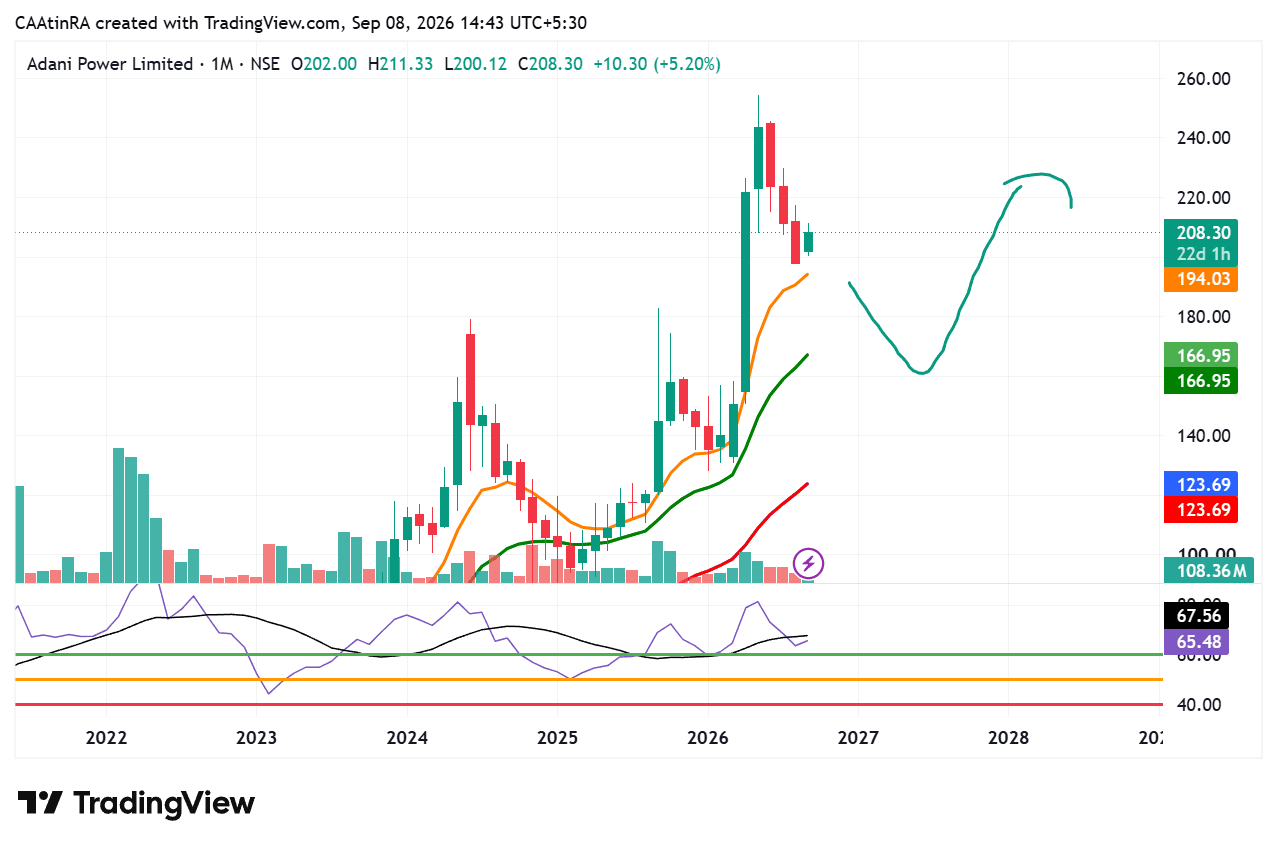
adani power wait for the levels mentioned in chart
ADANIPOWER
Adani Power (NSE: ADANIPOWER) is currently an interesting combination of strong operating fundamentals + a much lower valuation than its previous peak, but the stock remains technically sensitive.
1. Fundamental Analysis
The latest Q1 FY27 numbers are quite strong:
Parameter Q1 FY27 YoY
Continuing Revenue ₹17,936 Cr +26.6%
Continuing EBITDA ₹6,983 Cr +21.6%
PAT ₹4,867 Cr +47.2%
Power Sale Volume 28.8 BU +16.9%
Plant Load Factor ~78% Improved
These figures indicate that the improvement is not merely accounting-driven—power generation, volumes and profitability all improved.
A particularly positive point is that finance cost increased only about 5.2%, despite acquisitions and ongoing capex.
2. Growth Story
The biggest long-term trigger is capacity expansion.
Adani Power is targeting a portfolio of around 45 GW, while also expanding through acquisitions and new projects. It has also signed a 25-year agreement with MSEDCL for 1,600 MW from a planned ultra-supercritical project.
The thermal power cycle is also supportive because India's electricity demand is growing.
3. Debt — Important Risk
Debt is the area I would monitor carefully.
As of June 30, 2026:
Total debt: ₹58,381 Cr
Net debt: ₹47,643 Cr
Debt has increased from March 2026 as the company is expanding and acquiring assets.
So the story is:
High growth + high capex + high cash generation, but investors need to ensure that debt doesn't grow faster than operating cash flows.
4. Technical View
The stock has undergone a major correction from its previous highs, which has substantially changed the risk-reward profile.
A recent market report had the stock around the ₹400 area after a large correction from its previous 52-week high.
For chart analysis, I would focus on:
Previous swing high/low
20 EMA
50 DMA
200 DMA
Volume breakout
Weekly trend reversal
The most important signal would be a higher high + higher low formation on the weekly chart with strong volume.