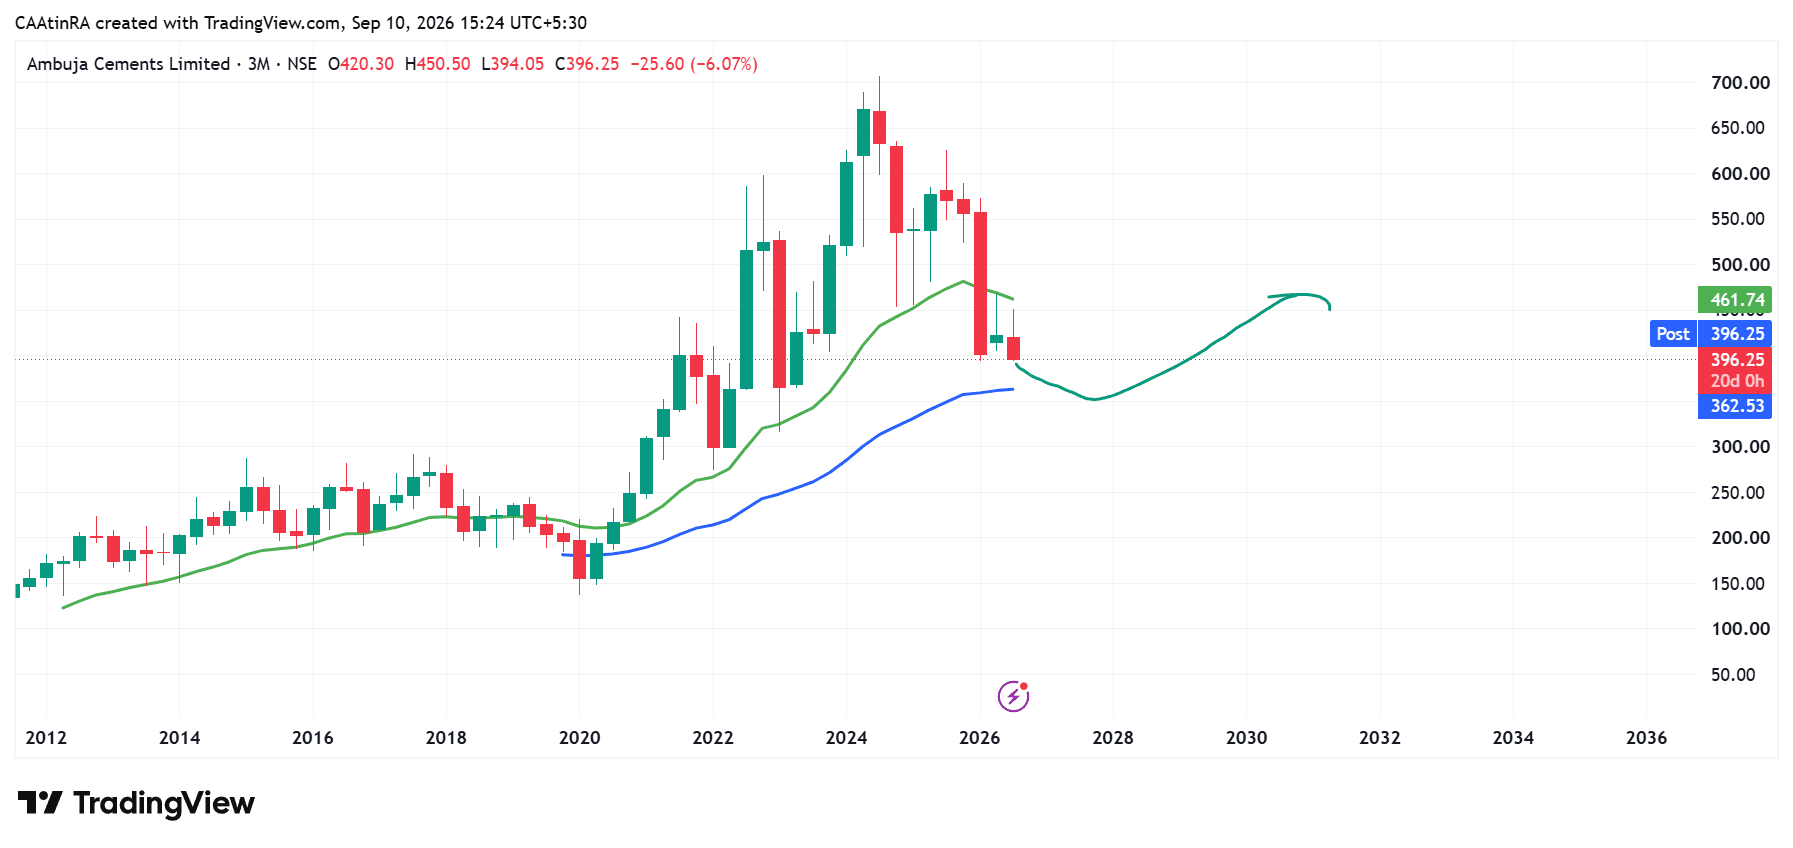
Ambuja Cements Ltd. is India's second-largest cement player under the Adani Group after the acquisition of ACC.
Business Snapshot
Particular
Details
Sector Cement & Building Materials
Parent Group Adani Group
Market Cap Around ₹1 Lakh Crore.
Installed Capacity Over 100 MTPA and expanding aggressively.
Brands Ambuja Cement, ACC, premium cement products.
Why Ambuja is Important?
Massive infrastructure demand in India.
Housing demand remains strong.
Adani is expanding cement capacity rapidly.
Focus on renewable energy to reduce production cost.
The Financial Express
+1
2. Fundamental Analysis
Revenue & Profit Trend
5
Latest Quarterly Snapshot (Q1 FY27)
Metric
Trend
Revenue
Declined around 8% YoY.
Net Profit
Declined around 34–37% YoY.
EBITDA Margin Under pressure because of lower dispatches and fuel costs.
mint
Positive Point
Company remains profitable.
Balance sheet is very strong with low debt.
Cash generation continues to remain healthy.
mint
+1
Negative Point
Earnings disappointed in the latest quarter.
Volume growth slowed during monsoon.
Valuation Check
Parameter
Observation
P/E
Around 22x.
Sector P/E
Around 28x.
Valuation View Trading below sector average after correction.
mint
+1
Conclusion: Valuation has become more attractive than many cement peers.
Shareholding Pattern
Holder
View
Promoters
Strong holding around 67%.
Mutual Funds Increased holding.
FIIs Slight reduction recently.
mint
+1
Interpretation
Domestic institutions continue to accumulate.
Promoter confidence remains intact.
Trend
The stock is in a short-term downtrend.
Reason:
Trading below 20 DMA.
Trading below 50 DMA.
Trading below 100 DMA.
Trading below 200 DMA.
RSI
RSI around 35.
Indicates stock is approaching the oversold zone