‹ All Posts
CA ATIN AGRRAWAL

1 hour ago · SEBI Registration INH000020785

bajaj auto we need to wait strong support at 10500-10750
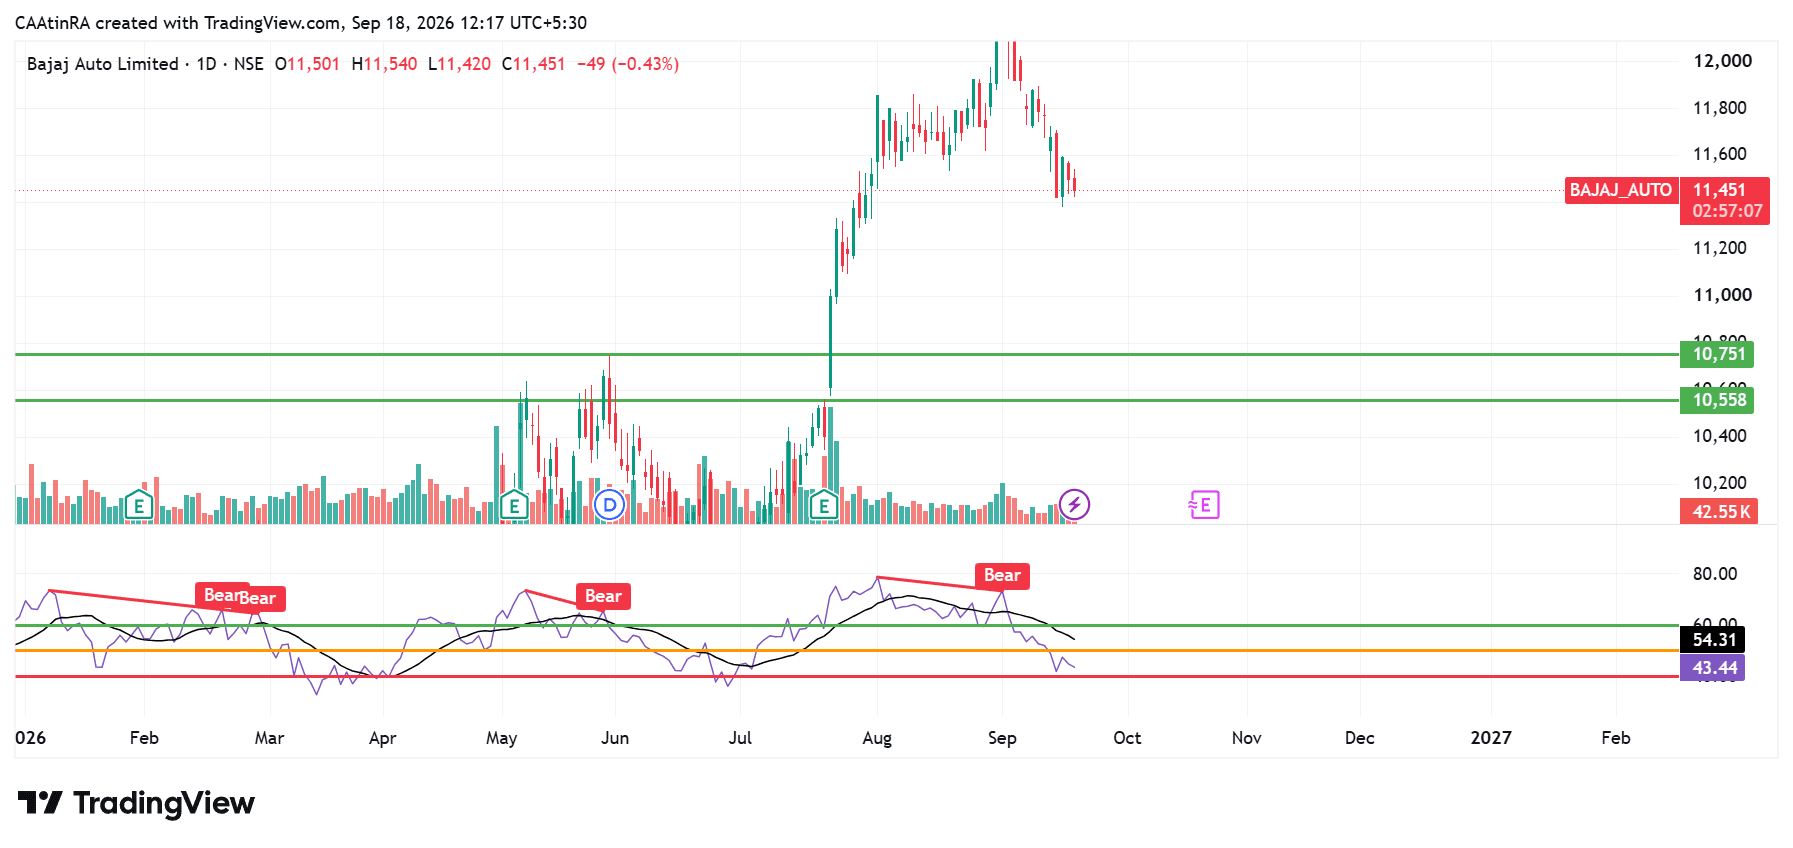
BAJAJ-AUTO
Bajaj Auto has entered FY27 with strong operating momentum. From a research perspective, the key factors to track are volume growth, export recovery, premiumisation, EV execution and margin sustainability. Fundamental observations: Q1 FY27 consolidated revenue was about ₹21,689 crore, up 65% YoY, while PAT rose about 46% to ₹3,226 crore. Total vehicle volumes increased 29% YoY to around 14.4 lakh units. Exports remain an important growth driver. Q1 exports increased 54% YoY to more than 7.3 lakh units, highlighting the company's recovery in international markets. FY26 was also strong, with revenue of ₹58,732 crore, EBITDA of ₹12,019 crore and PAT of ₹9,825 crore. EBITDA margin stood at 20.5%. The domestic premium motorcycle portfolio remains strategically important, with the 125cc+ segment contributing 77.5% of motorcycle sales in FY26. Research view From a SEBI Registered Research Analyst perspective, Bajaj Auto's current investment case can be assessed around three pillars: 1. Earnings growth: strong volume growth and premiumisation can support revenue and profitability. 2. Export + EV optionality: continued export recovery and scaling of Chetak/e-3W businesses could provide additional growth avenues. 3. Valuation vs. growth: after a strong earnings performance, investors should not evaluate the stock purely on historical performance; the sustainability of earnings growth and the valuation being paid for that growth remain important. Overall commentary: Bajaj Auto continues to show strong operating fundamentals, but investors should track the next few quarters for sustained volumes, margins, exports and EV profitability before drawing conclusions about the durability of the current earnings trajectory.

#EquityResearch#WatchOutFor#HiddenGems#FundamentalViews#Miscellaneous
BAJAJ_AUTO_2026-09-18_12-17-53.png
22 likes·23 comments