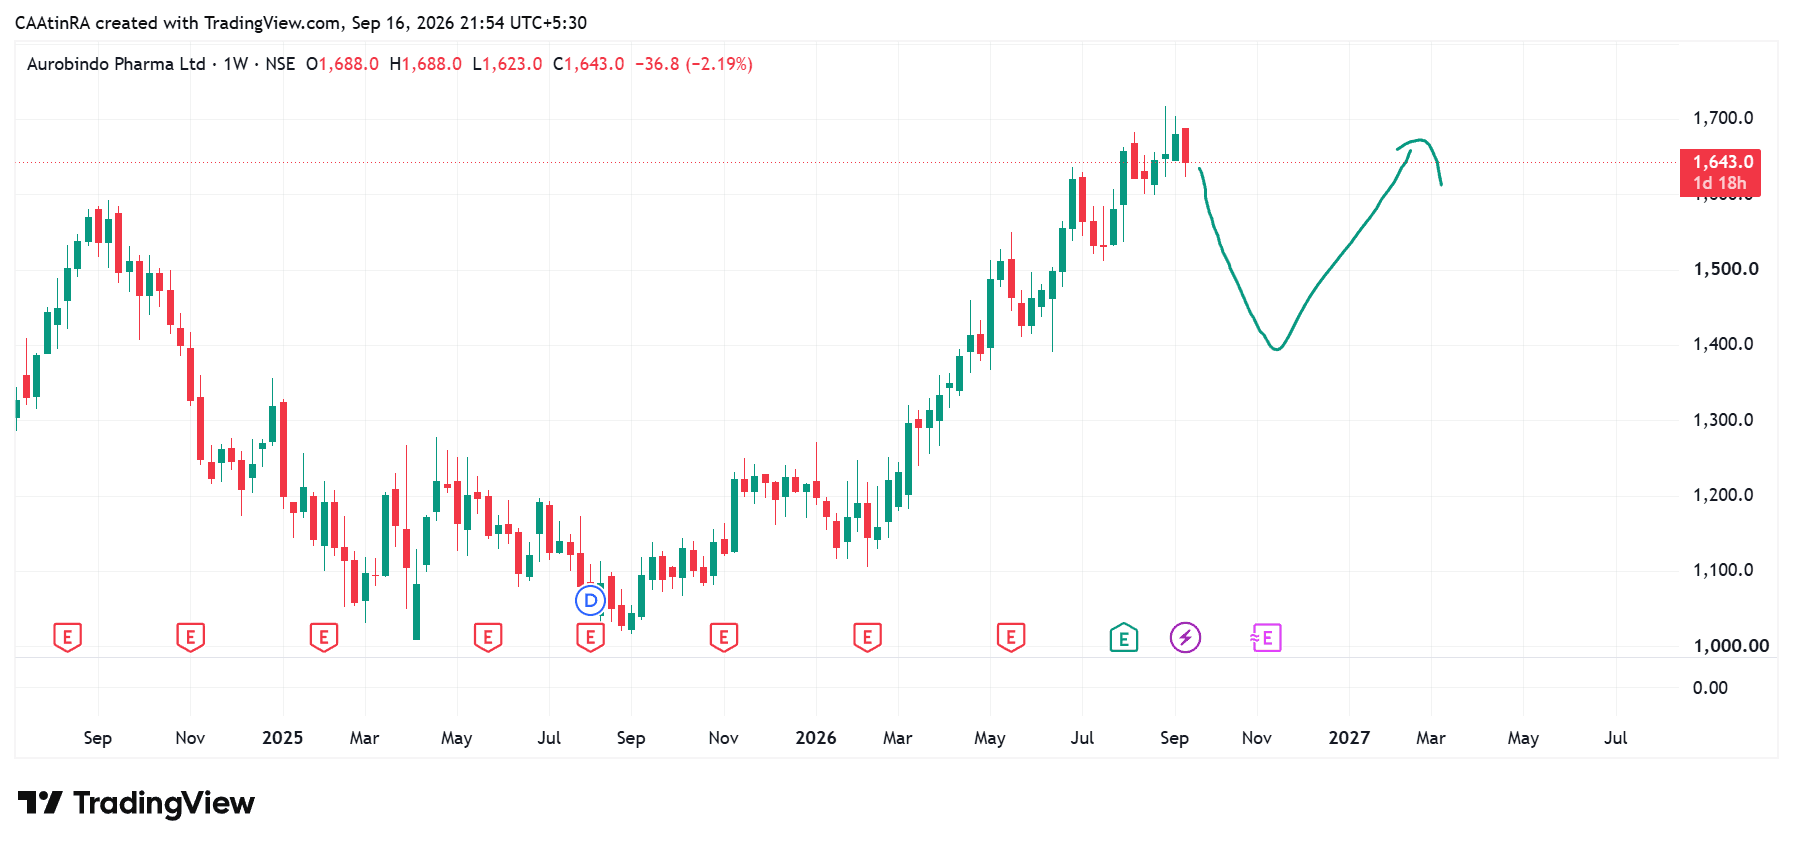
buy on dips stock near to resistance levels
1. Fundamental Analysis
Aurobindo Pharma is a large Indian pharmaceutical company with a strong presence in generic formulations, APIs and injectable products, with significant exposure to the US and European markets.
Q1 FY27 — Strong growth
Parameter Q1 FY27 YoY Growth
Revenue ₹9,150 Cr +16.3%
Operating Profit ₹1,839 Cr +14.7%
PBT ₹1,515 Cr +25.6%
Net Profit ₹1,032 Cr +25.2%
Revenue and net profit both reached strong levels, with Q1 FY27 revenue being the company's highest quarterly revenue.
Geographic performance:
Europe: +25.6% YoY
Growth Markets: +37.7%
US: +8.1%
API revenue: ₹1,049 Cr
The company received 10 final USFDA product approvals during the quarter.
2. Balance Sheet
The balance sheet is relatively comfortable.
FY26 Debt/Equity: around 0.21x
Net Debt/Equity: negative, indicating net cash position
FY26 ROCE: around 12.7%
FY26 ROE: around 9.9%
The company reported a net cash position of about ₹397 crore at the end of Q1 FY27, even after funding the Lannett acquisition and share buyback.
3. Valuation
At around ₹1,635–₹1,650, the stock is trading at approximately 26x trailing earnings based on current market data.
So, valuation is not extremely cheap, but the market is also pricing in improving earnings growth.
One thing to watch is whether the recent acceleration in earnings continues over the next few quarters.
4. Technical Analysis
This is where the chart becomes particularly interesting.
Current technical data shows:
5 DMA: ₹1,668
20 DMA: ₹1,651
50 DMA: ₹1,611
100 DMA: ₹1,545
200 DMA: ₹1,388
RSI: 48.38
MACD: Positive
ADX: 23.05
The important point is that the stock remains above the 50, 100 and 200 DMA, so the medium/long-term structure remains constructive.
However, short-term momentum has weakened after the stock tested ₹1,717.
Key levels
Resistance
₹1,685
₹1,710–₹1,717
₹1,730+
Support
₹1,638–₹1,650
₹1,610–₹1,620
₹1,590
₹1,545
These levels are also broadly consistent with current pivot calculations.
#WatchOutFor#EquityResearch#HiddenGems#Post-ClosingCommentary#FundamentalViews

 Equity Research
 Fundamental Views
 Hidden Gems
 Index Strategies
 International Market
 IPO
 Macro Views
 Miscellaneous
 Personal Finance
 Post-Closing Commentary
 Pre-Opening Commentary
 Psychology of Money
 Sector Breakout
 Stock In News
 Technical Views
 Time To Exit
 Today's Trading Setup
 Trending Sectors
 US Market
 Watch Out For