Ashok Leyland Limited, part of the Hinduja Group, is one of India's major commercial vehicle manufacturers. Its portfolio includes heavy and light commercial vehicles, buses, defence vehicles, engines and related mobility solutions.
Ashok Leyland reported consolidated revenue from operations of ₹13,069.59 crore in Q1 FY2026–27, an increase of 11.62% year-on-year. Consolidated net profit rose 1.53% to ₹667.77 crore. The company also recorded its highest-ever quarterly commercial vehicle sales volume of 48,763 units.
- Commercial vehicle demand: Freight movement, infrastructure investment and fleet replacement can support sales.
- Operating margins: Higher material costs can put pressure on profitability.
- Electric mobility: Switch Mobility offers potential growth opportunities, although execution and profitability remain important.
- Defence and exports: Expansion in these segments may diversify revenue sources.
- Cash generation: A strong cash position can support investment and business resilience.
Management has highlighted rising material costs as a concern while focusing on cost savings, improved product mix and better price realisation.
4. Technical Analysis and Important Price Levels
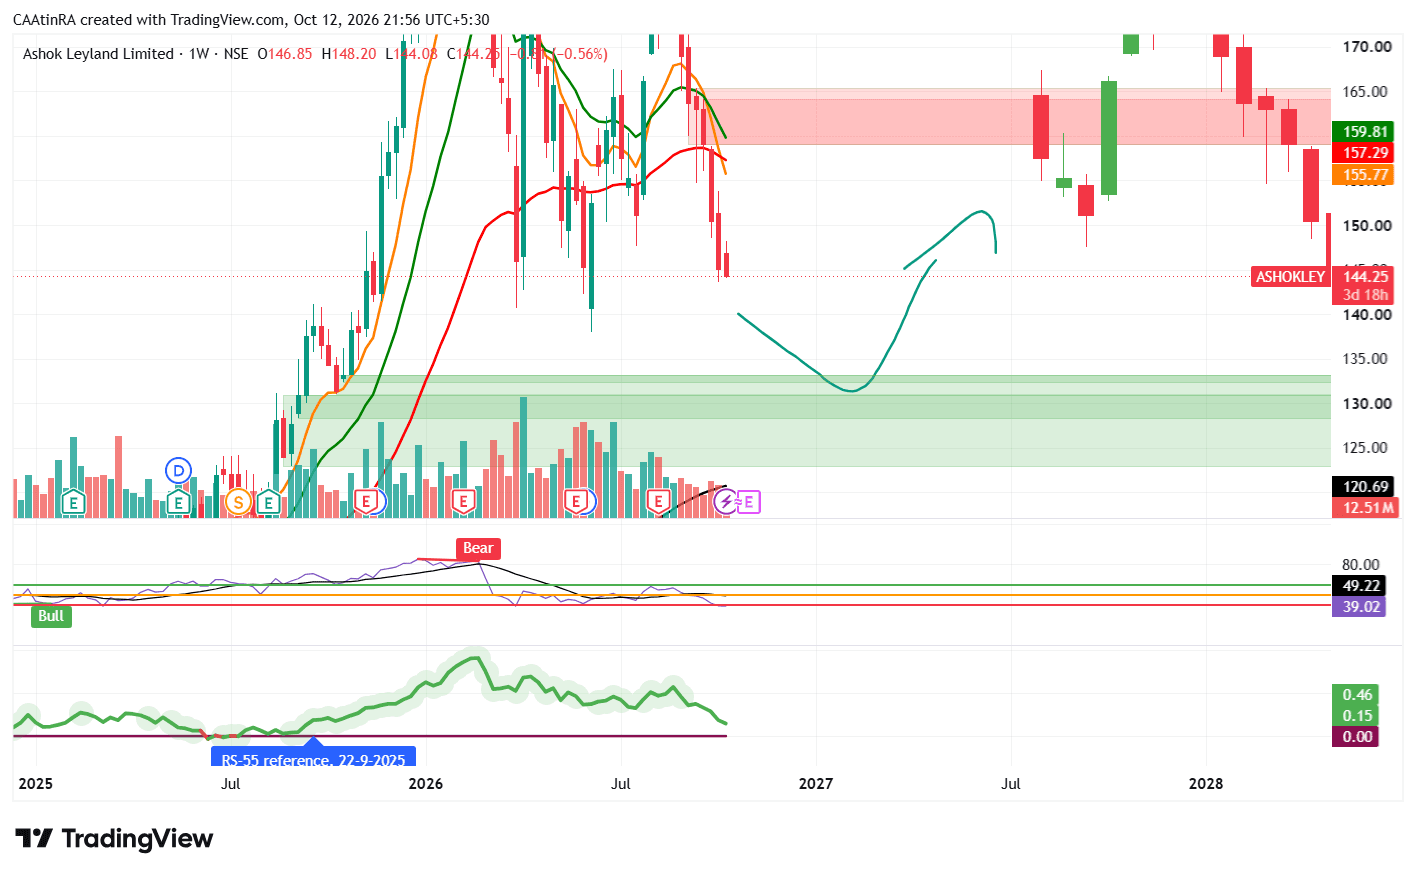
Based on the latest available technical data for 12 October 2026, the stock is trading below its major moving averages. The 20-day EMA is around ₹155.74, while the 50-day and 200-day EMAs are approximately ₹160.92 and ₹161.42, respectively. The reported RSI is near 29, indicating weak momentum and potentially oversold conditions.
Technical level Price zone
Immediate support ₹143–₹144
Important support ₹141–₹142
Lower support ₹137–₹140
Immediate resistance ₹147–₹149
Strong resistance ₹151–₹153
Major resistance ₹156–₹161