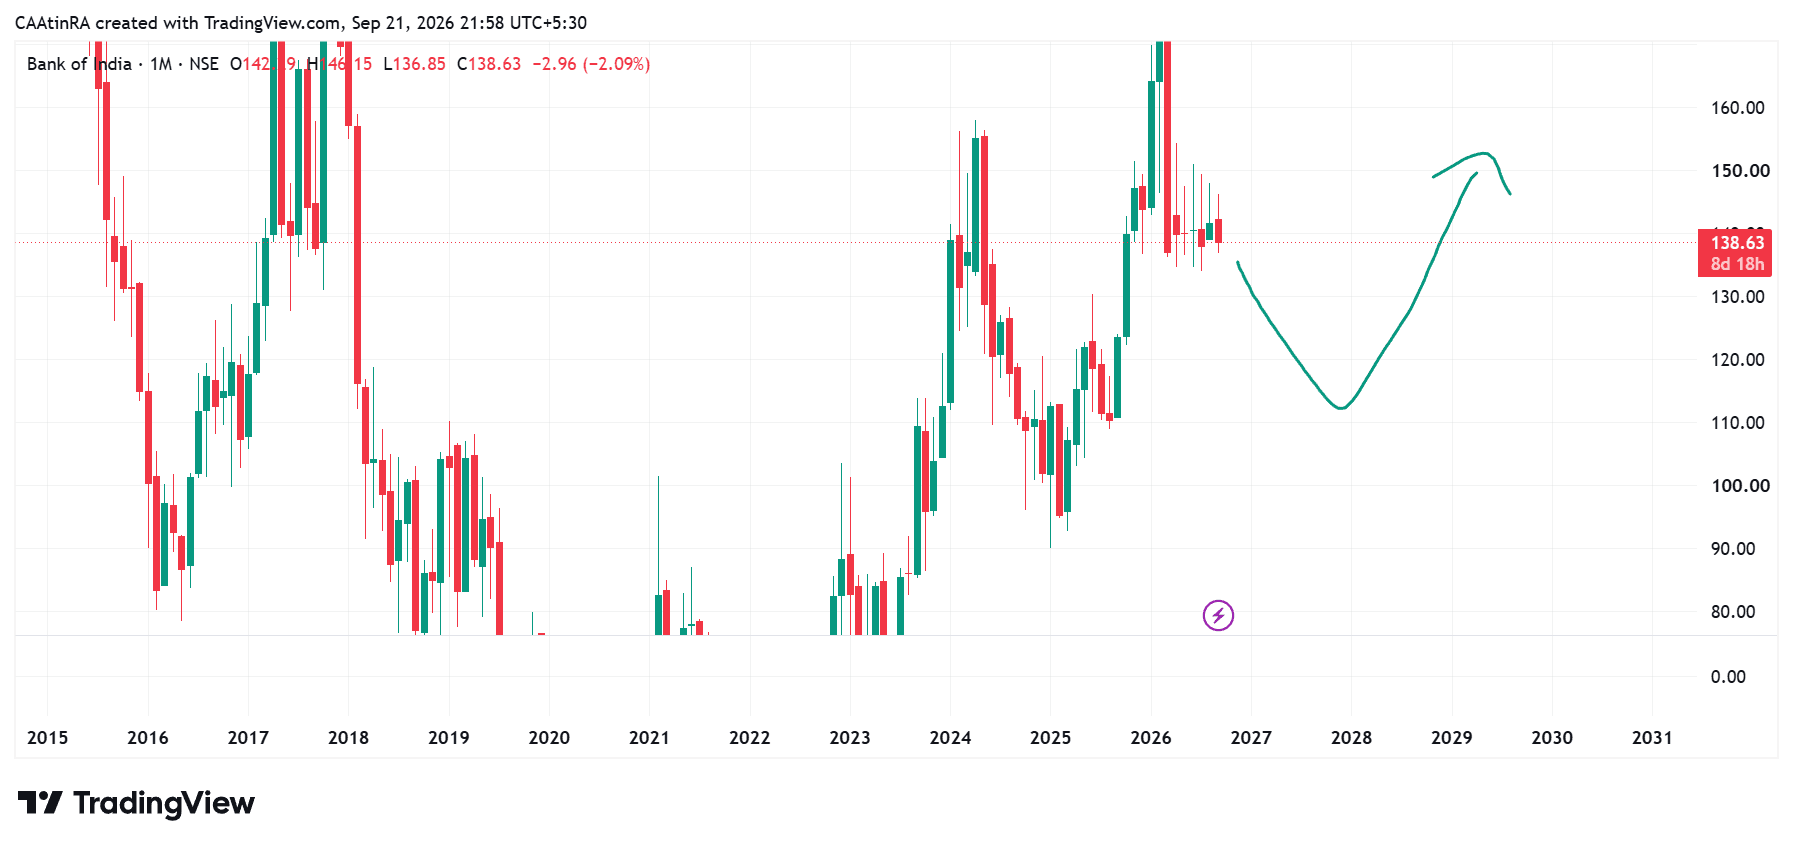
Bank of India (BANKINDIA) has shown a meaningful improvement in its operating and asset-quality metrics in Q1 FY27. The bank reported ₹3,068 crore net profit, up 36.23% YoY, while NII increased 12.61% YoY to ₹6,833 crore.
Key positives
Loan growth: Global advances grew 18.64% YoY, with retail advances up 20.60%.
Asset quality: Gross NPA improved to 1.81% from 2.92% YoY, while Net NPA declined to 0.51% from 0.75%.
Slippages: Slippage ratio improved to 0.24% versus 0.33% a year earlier.
Capital position: Capital adequacy ratio stood at 18.69%, with CET1 at 15.97%.
Management has indicated continued focus on lowering the cost of deposits and supporting credit growth through FCNR(B) deposits and overseas funding.
Important watch points
The major area to monitor is NIM, which moderated slightly to 2.52% from 2.55% YoY. For a banking stock, sustaining loan growth while protecting margins will be important for earnings momentum.
From a risk perspective, management said it is closely monitoring sectors affected by the West Asia situation, particularly chemicals, ceramics and businesses exposed to import/export activity.
My research view
Bank of India is showing a combination of strong credit growth, improving asset quality and rising profitability. However, investors should not evaluate the stock only on the basis of one quarter. The next few quarters' NIM trajectory, credit growth, slippages, GNPA/NNPA and provision requirements will be important indicators.
At the latest market data available for 21 September 2026, Bank of India was around ₹138.40–₹139.61, with a 52-week range of approximately ₹116–₹178.36.