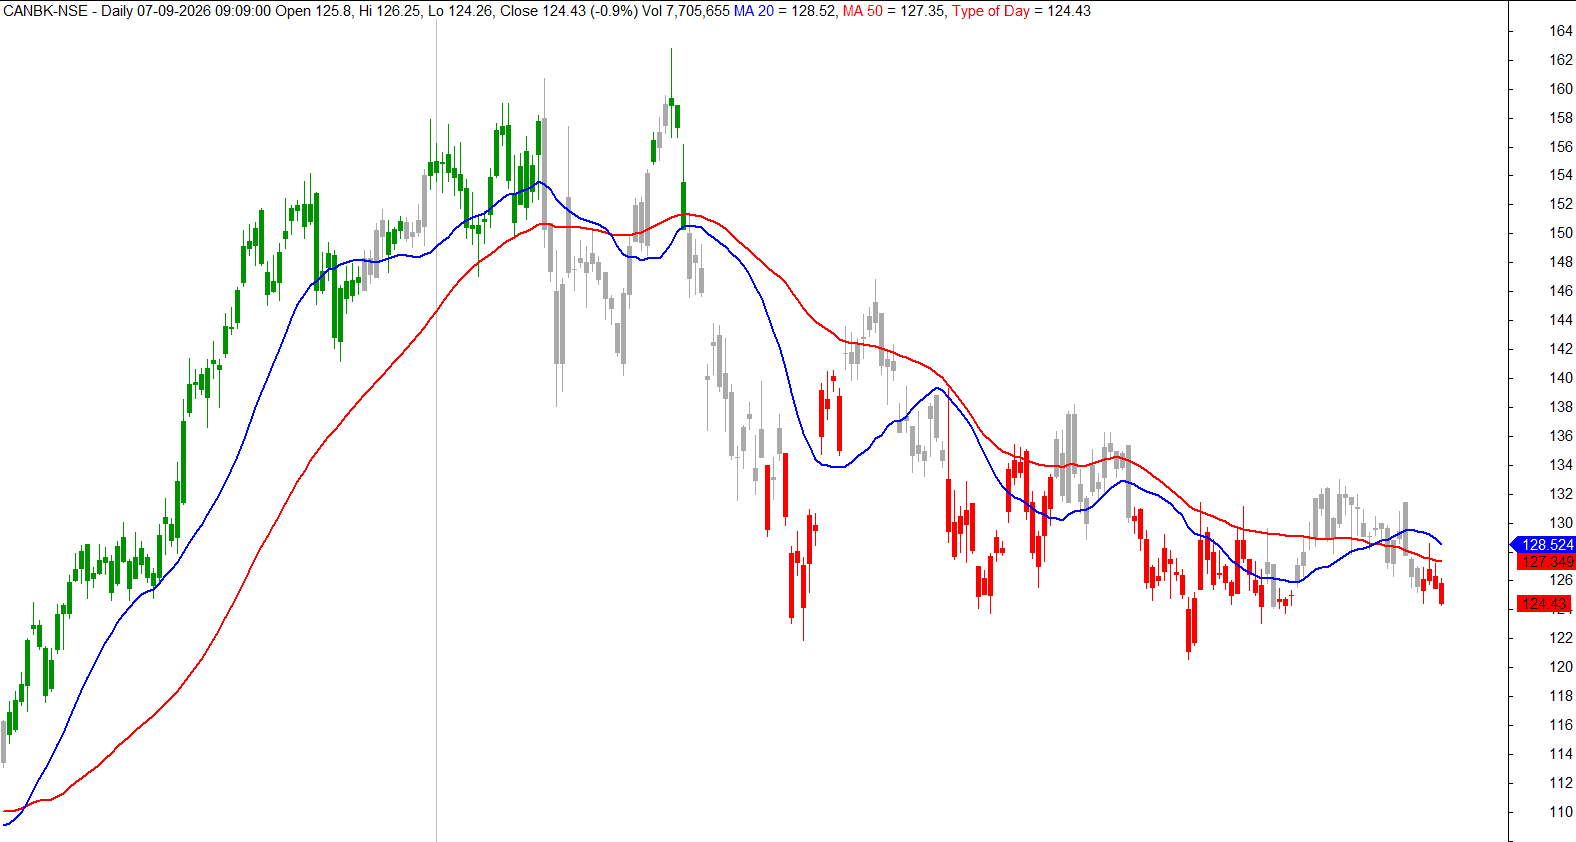
CANARA Bank , Bearish Crossover, Lower targets, be cautious
CANBK
reported standalone Q1 FY27 net profit of about Rs 4,856 Cr, up only 2.2% YoY, even though net interest income grew 13.4% to roughly Rs 10,215 Cr. Asset quality improved sharply, with gross NPA down to 1.57% and net NPA at 0.36%. Advances grew 19% while deposits grew 11.6%.
That gap between 13% NII growth and 2% profit growth is the thing to understand. Falling provisions have been flattering bank profits for a while, and once they are already low that tailwind is spent. Deposits growing slower than loans also pressures funding cost. Those are the two risks worth tracking.
The chart is where the useful bit sits, because it refuses to give a clean answer.
Price at 125.50 is below the 20 EMA at 127.77 and the 50 EMA at 128.60. The two averages are just 83 paise apart. RSI is 41, down from 61 twenty sessions ago.
Apply the slope test on the 50 EMA and you get minus 0.22% over 20 sessions. Essentially zero.
That is not a failed test, it is an answer. A flat slow average means the market has no directional view on this stock right now, and the readings that look bearish are just short term noise inside a range. This is the third state, alongside a rising average and a falling one, and it is the most common of the three.