MTNL is a government-owned telecom company providing services primarily in Delhi and Mumbai, but its financial position remains highly stressed due to declining revenue, heavy debt and substantial interest expenses. In FY 2025–26, the company’s standalone operating revenue declined to approximately ₹887 crore from ₹1,061 crore in FY 2024–25, while its net loss remained around ₹3,103 crore, highlighting continuing financial challenges. On the positive side, government support, asset monetisation and operational management by BSNL under a service-level agreement provide some support to its business. According to government statements reported in July 2026, MTNL’s total liabilities reached approximately ₹40,009 crore, although its non-core assets were valued at around ₹50,000 crore, and its EBITDA improved to ₹437 crore in FY26. However, the improvement in EBITDA does not mean the company has become profitable at the net-profit level, as interest costs remain extremely high.
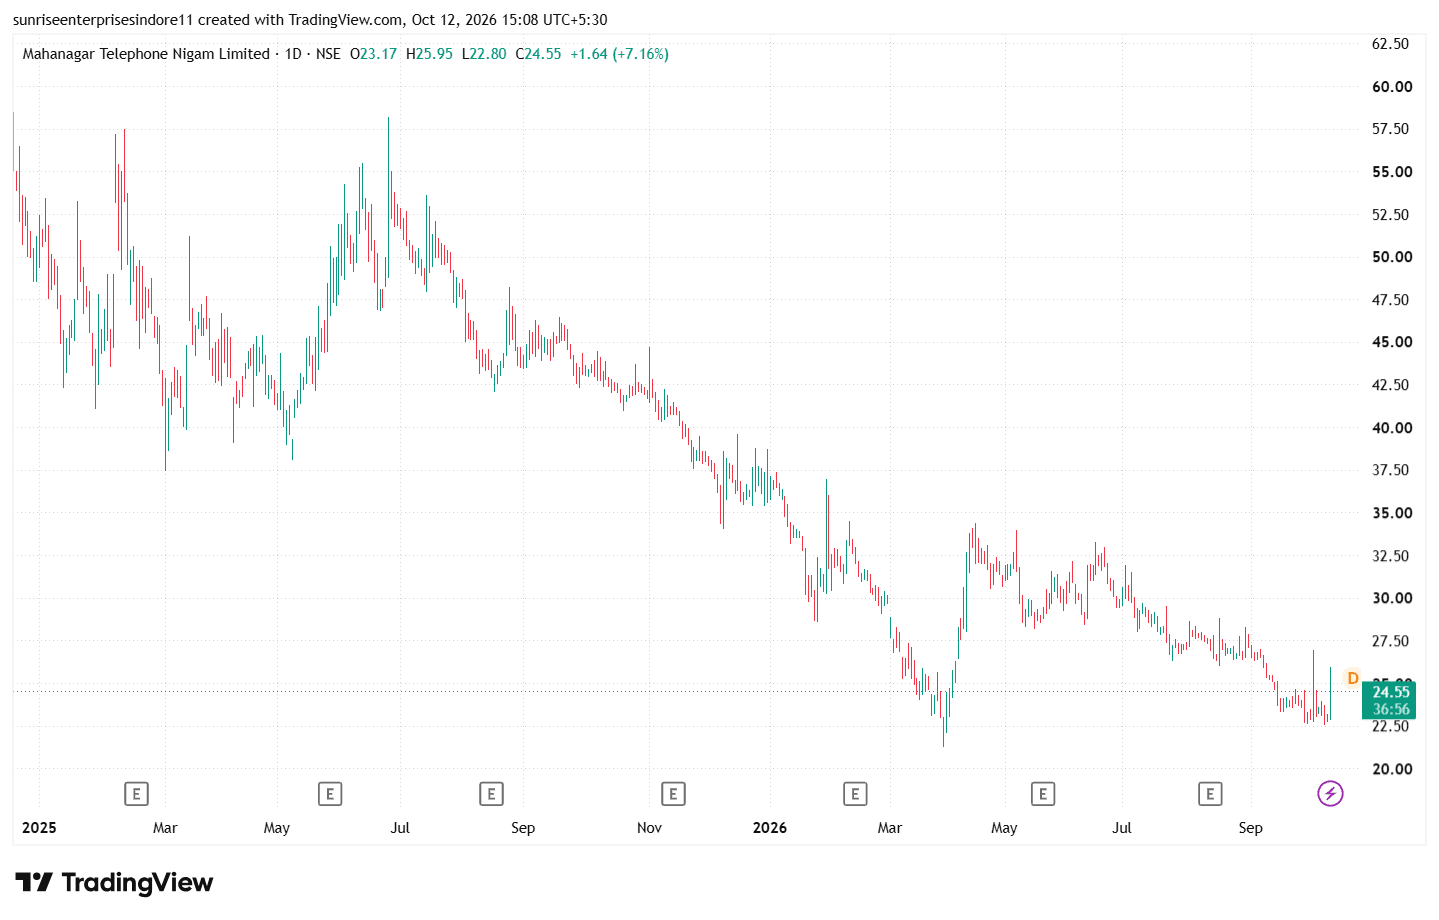
Overall, MTNL remains a high-risk, turnaround-oriented PSU stock. Any sustained improvement in its financial position, successful asset monetisation or progress on the BSNL merger could support investor sentiment, but heavy liabilities, continued losses and liquidity concerns remain major risks. Investors should monitor quarterly results, debt servicing and official government announcements rather than relying solely on speculative revival expectations. This analysis is for educational purposes only and is not investment advice.