Tata Steel has a mixed but improving fundamental outlook
TATASTEEL
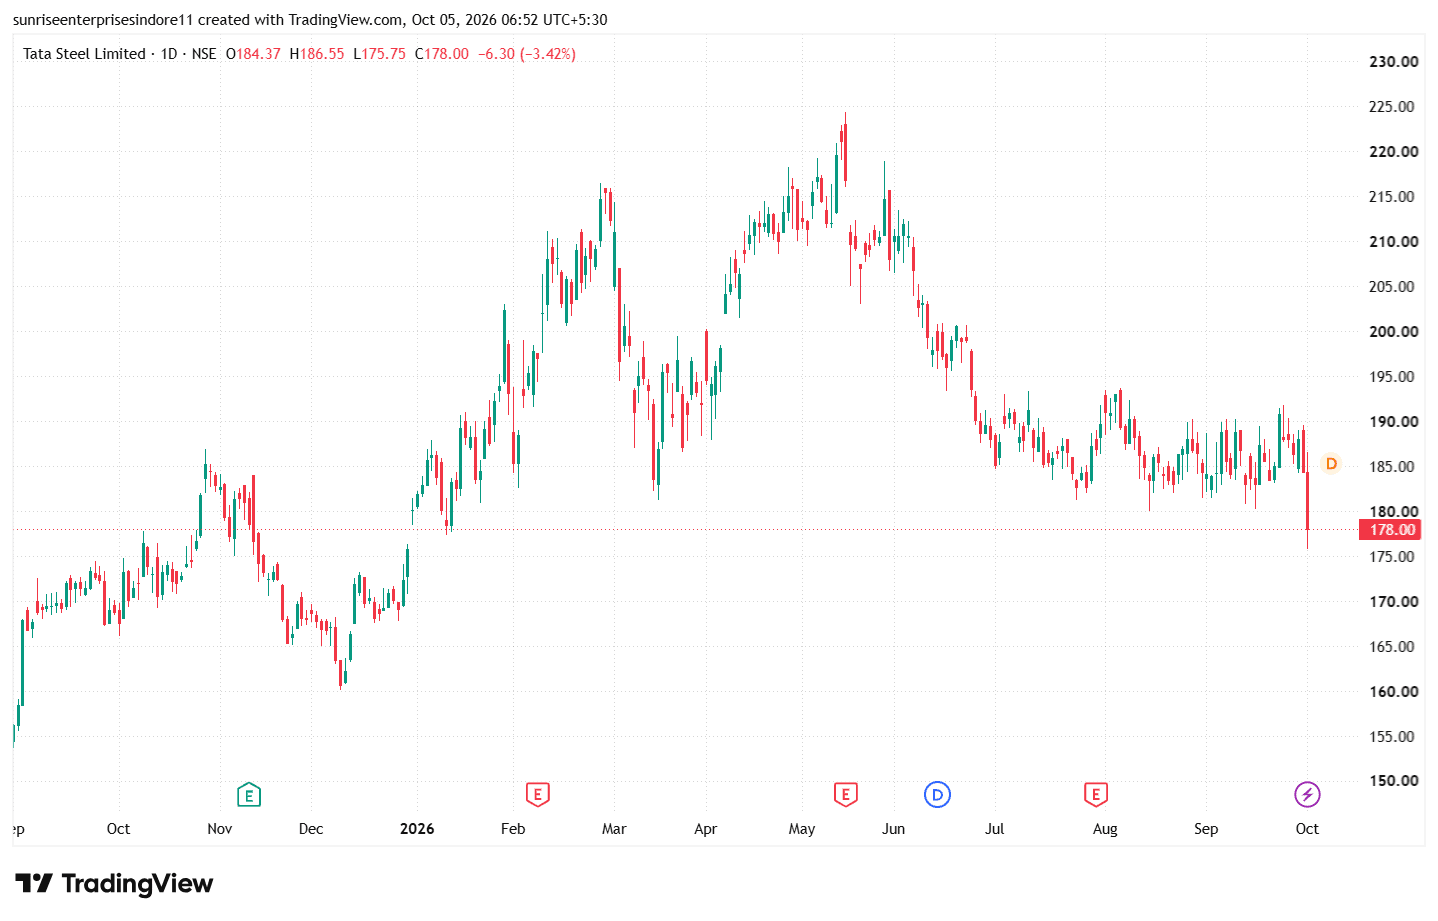
Tata Steel has a mixed but improving fundamental outlook: the company’s Q1 FY27 performance was strong, with consolidated EBITDA rising 25% YoY to ₹9,370 crore, while the India business delivered a healthy 27% EBITDA margin, supported by better steel realisations and improved per-tonne profitability. India’s steel demand outlook is also positive as the government targets 600 million tonnes of steelmaking capacity by 2047, while post-monsoon infrastructure and auto demand is expected to support domestic steel prices. On the expansion front, Tata Steel’s Board approved a 4.8 MTPA capacity expansion at Neelachal Ispat Nigam, involving estimated capex of ₹33,873 crore, which could strengthen its long-term domestic growth story. The company is also progressing with its ~3 MTPA electric arc furnace at Port Talbot, although the UK business remains a near-term drag as Q1 EBITDA loss stood at £27 million. In the Netherlands, Tata Steel and the Dutch government have extended their Green Steel project agreement by five months to March 2027, indicating continued progress but also highlighting delays and unresolved investment/regulatory issues. Overall, improving Indian margins, higher domestic steel demand, capacity expansion and green-steel investments are positive catalysts, while elevated coking-coal costs, European operations, UK turnaround execution and large capex requirements remain key risks for the stock.