‹ All Posts
Mayank Kumar

6th Oct · SEBI Registration INH000015978

The food-delivery business also remained healthy
ETERNAL
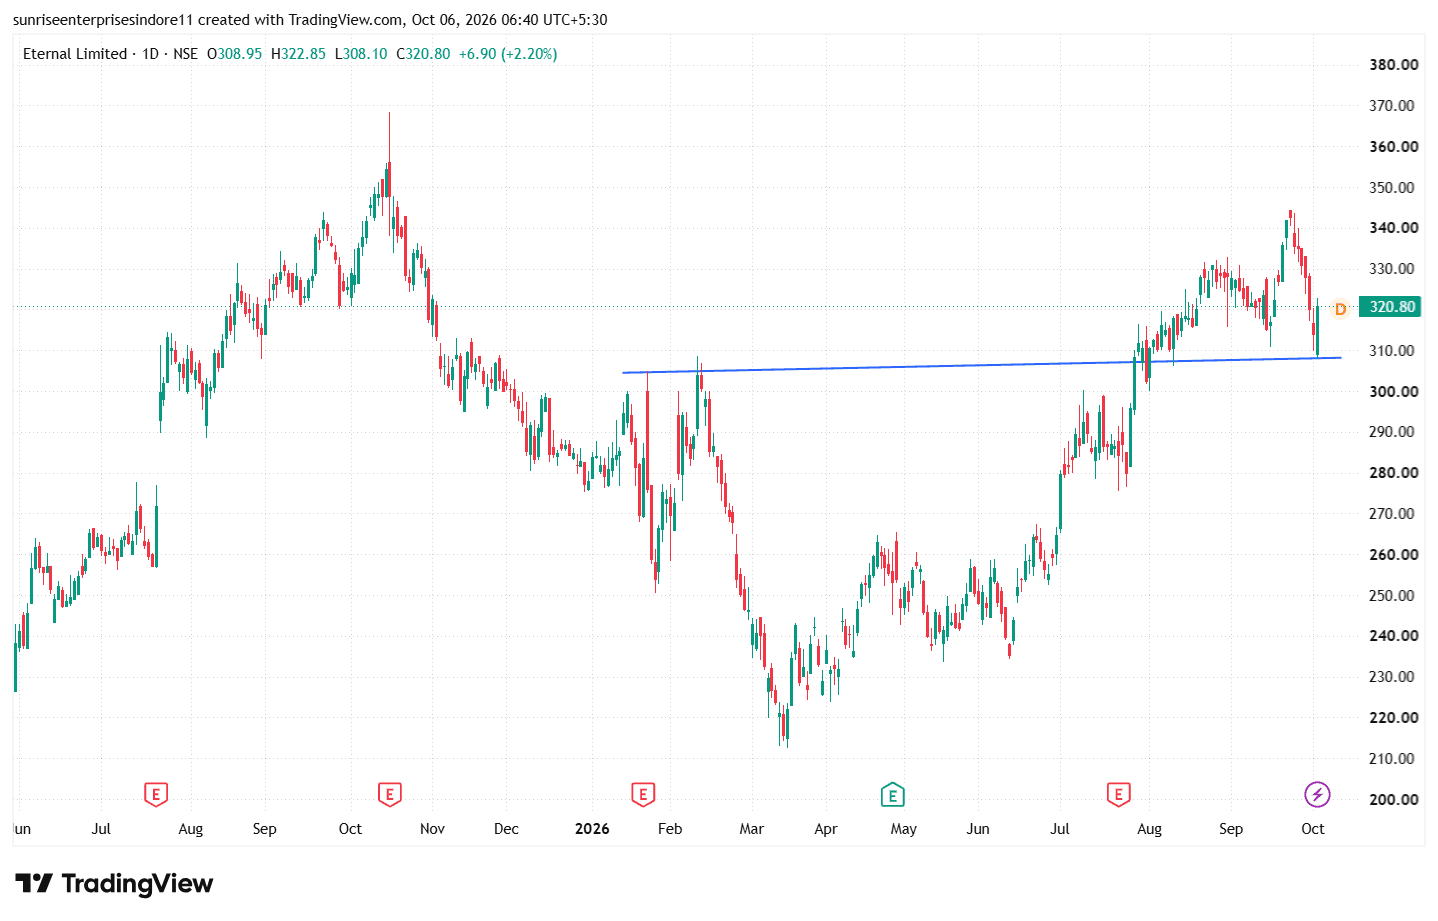
The food-delivery business also remained healthy, with revenue up 33.1% YoY to ₹3,537 crore, NOV up 20.1%, and adjusted EBITDA reaching ₹606 crore. Hyperpure, although revenue declined sharply, moved into positive adjusted EBITDA, while District/Going-Out continued to grow but remains loss-making. A major medium-term positive is the expected operating leverage from Blinkit's expanding network. S&P Global expects Eternal's FY27 net income to rise sharply, with Blinkit becoming an increasingly important earnings contributor as newer dark stores mature and sales density improves. Goldman Sachs has also maintained a Buy view and recently raised its target price from ₹345 to ₹385, projecting that Eternal could reach $1 billion EBITDA by FY29. Latest stock-market angle: Eternal closed at ₹320.80 on 5 October, up 2.2%, with a 52-week range of ₹212.60–₹368.45. The key fundamental positives are therefore Blinkit's transition to profitability, rapid quick-commerce growth, improving food-delivery margins and expected operating leverage. The major risks remain high valuation, continued aggressive competition in quick commerce, heavy expansion/investment requirements and losses in newer businesses. NSE currently shows the stock's P/E as extremely elevated, so strong future earnings growth is already important to justify the valuation.

#FundamentalViews
ETERNAL_2026-10-06_06-40-35.png
896 likes·50 comments