40 mins ago · SEBI Registration INH000019309
SEBI Registration INH000019309 · 40 mins ago
Pharma Rally, But Why Is Lupin Still Under Pressure?
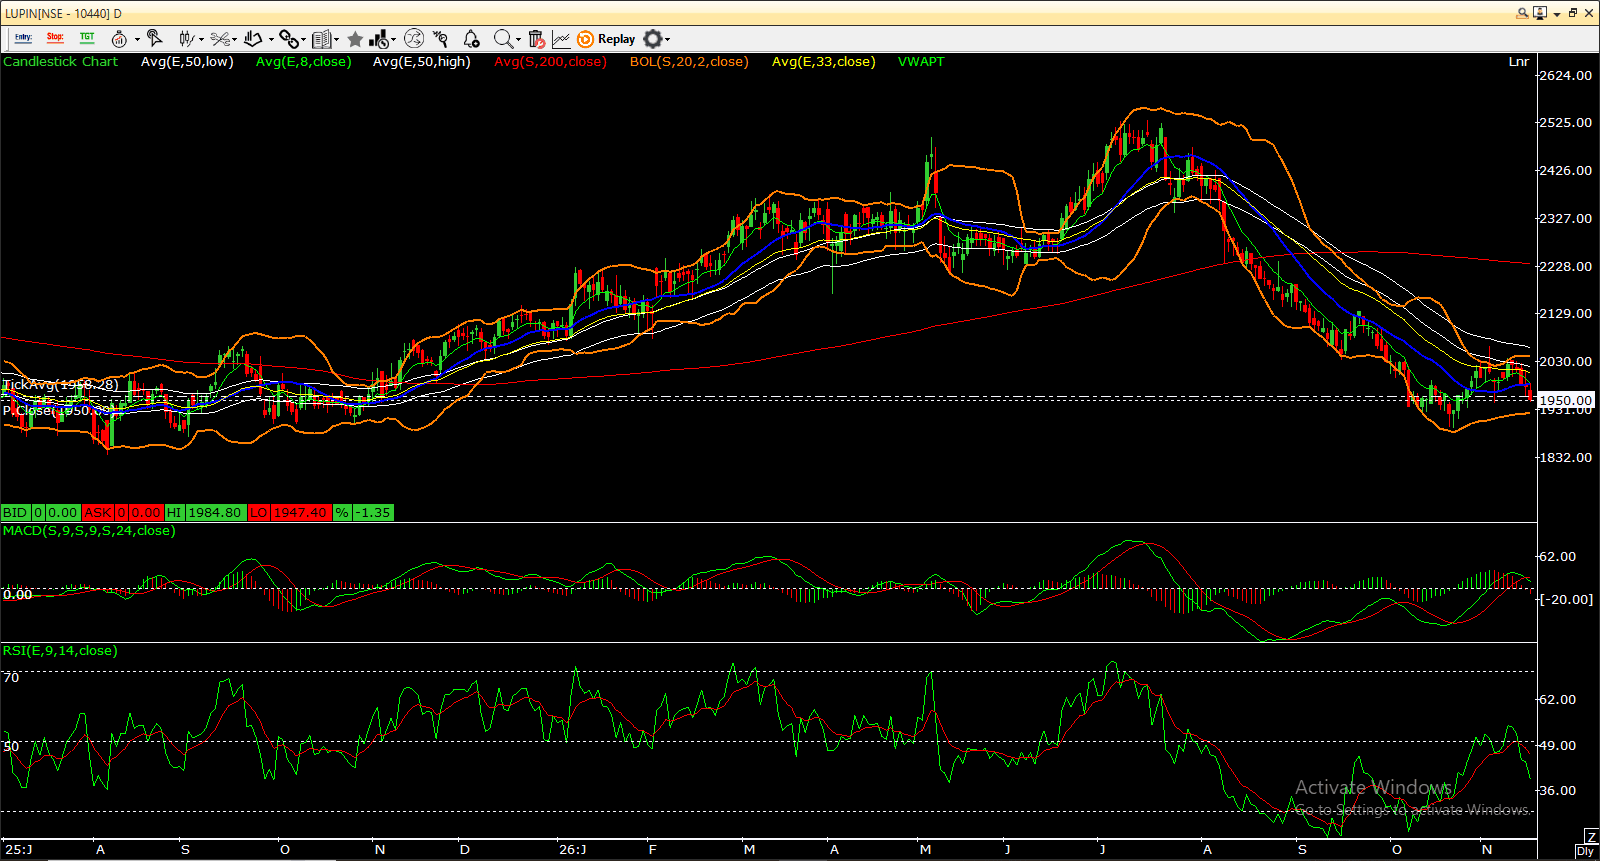
While several pharma stocks are witnessing renewed buying interest, Lupin is struggling to recover. The reason appears to be a combination of earnings pressure, US market competition and weakening technical momentum. What's Going Wrong? Lupin's Q2 FY27 results explain much of the concern: Revenue increased 14% YoY to ₹7,786 crore. EBITDA declined 10.7% to ₹2,171 crore. Net profit fell 22.2% to ₹1,155 crore. EBITDA margin contracted sharply from 35.6% to 27.9%. The biggest concern is the US business, which contributes nearly 39% of total sales. Increased competition in key products, particularly generic Tolvaptan and Mirabegron, is creating pricing and margin pressure. Higher employee, R&D and manufacturing expenses are adding to the challenge. India remains a bright spot, with domestic sales growing 14.7%. However, strong domestic growth is currently not enough to offset pressure in the US business. What Does the Chart Say? Lupin's daily chart reflects a prolonged correction from its July highs. The stock is struggling below its major moving averages, while the recent recovery is losing momentum. RSI is slipping towards the weaker zone, and MACD is showing signs of fading bullish momentum. The ₹1,950 zone is an important near-term support, while ₹2,030–2,100 is an overhead resistance area to watch. My View Lupin's weakness is not simply a case of missing the pharma rally. The market is repricing its near-term earnings and margin expectations. Until US business visibility improves and the stock regains its important moving averages, a cautious approach is warranted. A sustained breakout above resistance could change the technical picture. Disclosure: The analyst or his family does not have any position in Lupin. LUPIN