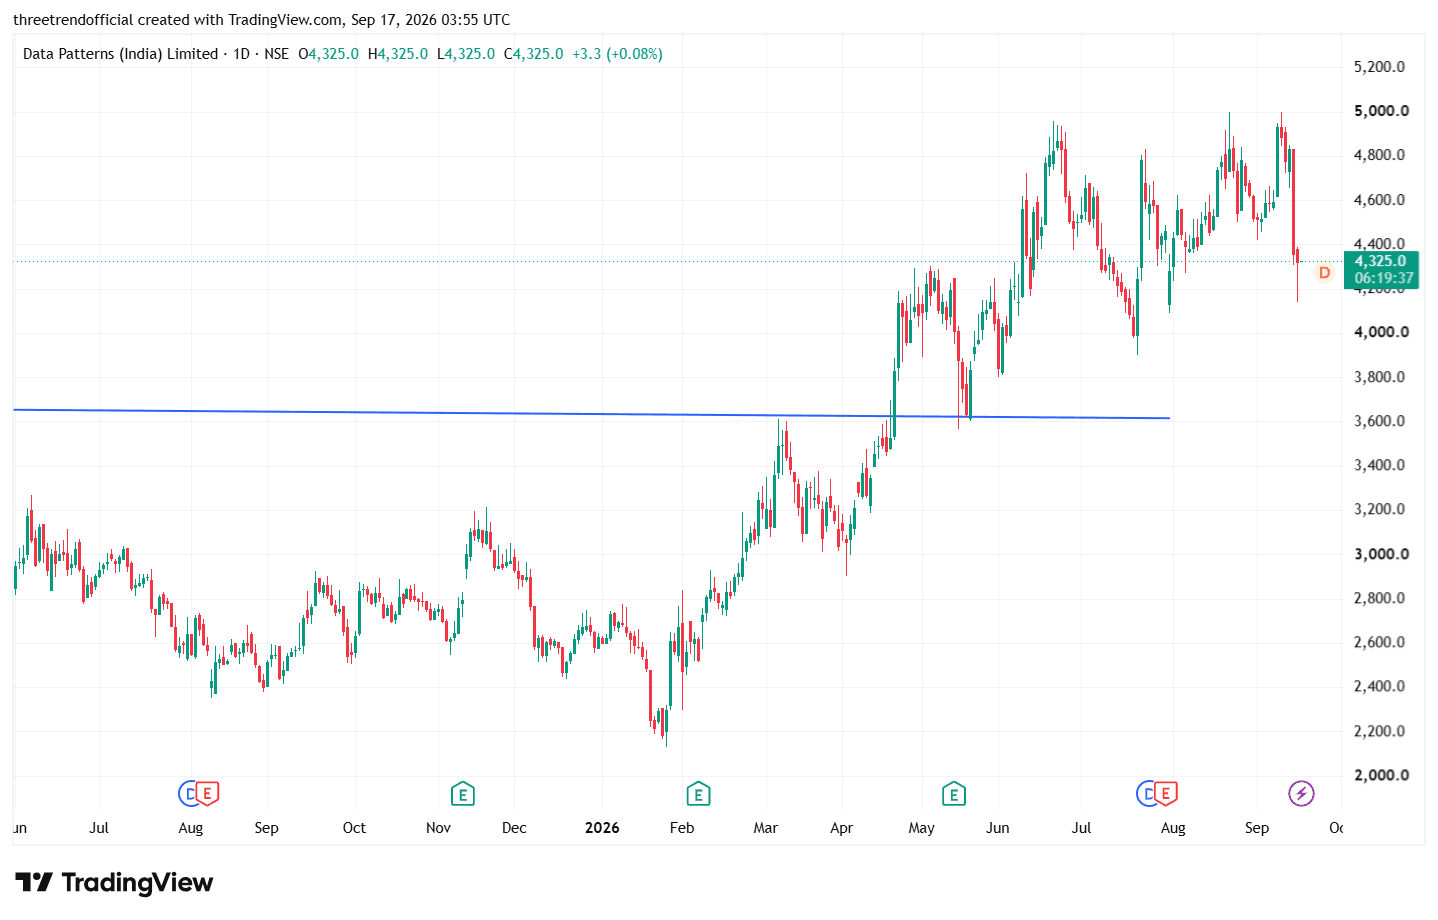
Data Patterns is rising mainly because of a defence
DATAPATTNS
Data Patterns is rising mainly because of a combination of strong defence-sector sentiment, large order inflows and expectations of sustained growth. The biggest recent company-specific trigger was a ₹585.76 crore radar-electronics order from BEL, taking post-July order inflows to about ₹771 crore and strengthening its order visibility. The broader defence sector has also received a boost after the Defence Acquisition Council approved around ₹1.1 lakh crore of procurement, with a high domestic-content component, which supports the long-term opportunity for defence-electronics companies such as Data Patterns. Management has retained its FY27 target of 20–25% revenue growth, expects around ₹2,000 crore of fresh orders, and guides for 35–40% EBITDA margin. The stock also showed strong technical momentum recently, gaining 5.5% during September 7–11 and approaching its ₹5,000 52-week-high area. However, there is an important caution: Q1 FY27 PAT fell about 13.5% YoY despite 16.8% revenue growth, highlighting that defence-order execution can be lumpy and that the market is already pricing in substantial future growth. In simple terms: Data Patterns is rising because investors are focusing on the large defence opportunity, fresh BEL orders, strong order visibility and FY27 growth expectations, while the main risks are high valuation, execution timing and the sustainability of earnings growth.