HFCL has corrected sharply from its 52-week high of ₹256.70
HFCL
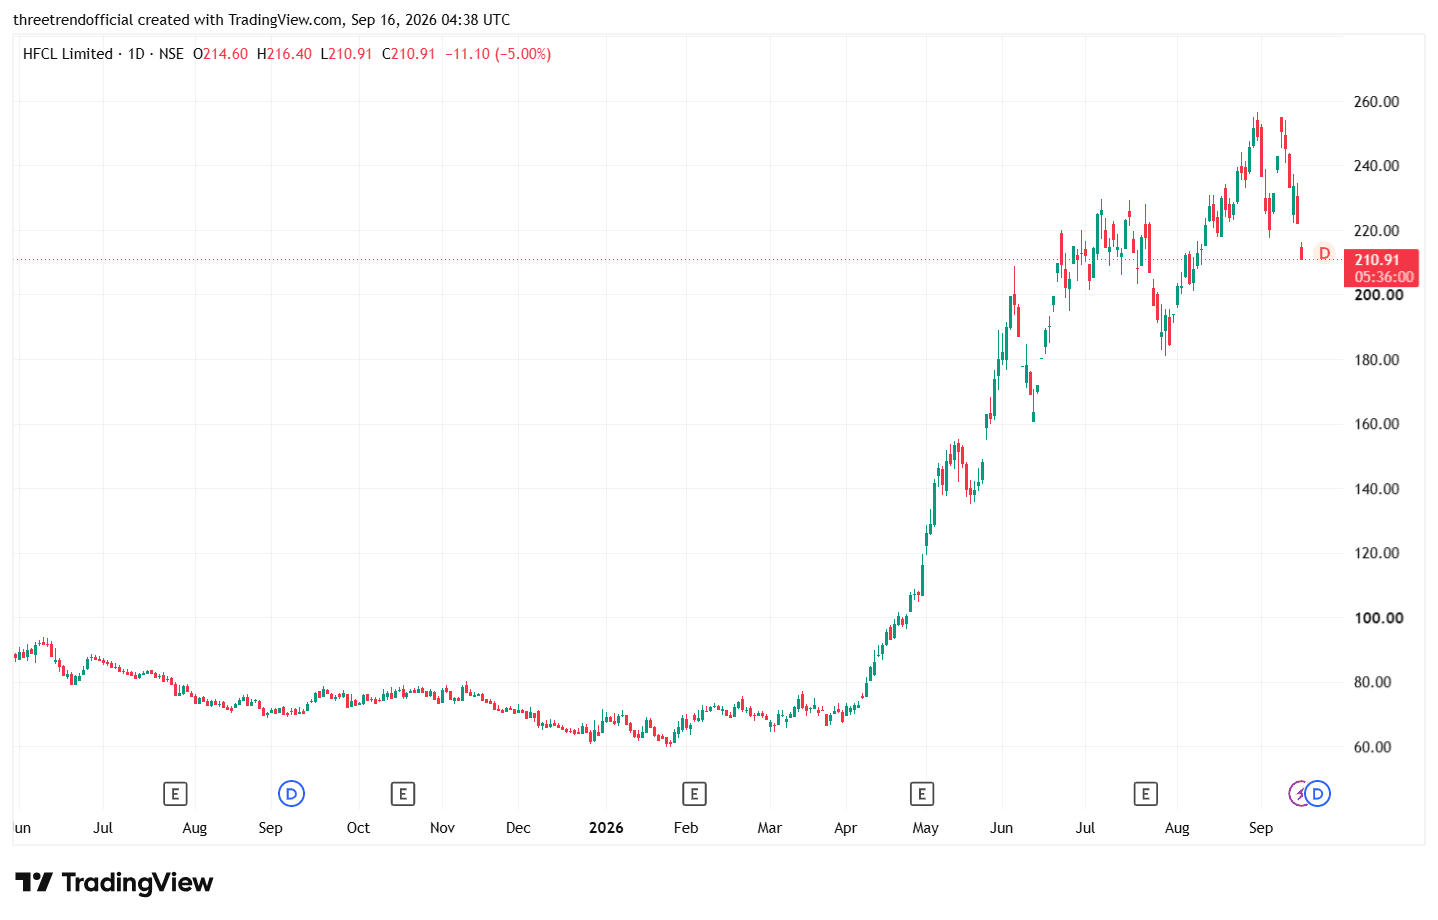
HFCL has corrected sharply from its 52-week high of ₹256.70 on August 31 to around ₹210.91, a fall of roughly 18%, with repeated 5% lower-circuit pressure largely after an extraordinary rally of more than 200% in 2026; recent reports point primarily to heavy profit booking and momentum reversal, while the latest ₹820 crore capacity-expansion announcement may also be making investors reassess near-term capex and funding requirements. Fundamentally, however, the business has recently shown strong improvement: Q1 FY27 revenue more than doubled to ₹1,914.98 crore, PAT reached a record ₹245.64 crore versus a ₹29.3 crore loss a year earlier, management increased FY27 revenue-growth guidance from 20% to 40%, and the company reported an order book of about ₹26,665 crore. HFCL also signed a three-year OFC supply agreement worth approximately ₹2,329 crore on September 1, while on September 14 the board approved an additional ₹820 crore investment in optical fibre, OFC and preform capacity, taking planned expansion capex to around ₹1,800 crore; HFCL says its OFC and connectivity-solutions order book alone is around ₹19,000 crore. Therefore, the present decline looks more like a sharp valuation/momentum correction after a huge rally rather than a confirmed collapse in operating fundamentals, although continued lower circuits indicate very weak short-term sentiment. Technically, the earlier ₹218–₹220 support has now broken, making it a resistance area; around ₹200–₹205 becomes the next important psychological/support zone, while a sustained recovery above ₹218–₹220 would be an early sign that selling pressure is easing. If ₹200 also breaks decisively, the correction could extend further, so price stabilization, volumes and any new exchange filings should be monitored closely.
For educational and informational purposes only, not investment advice.