Cipla is a leading Indian pharmaceutical company with a strong presence in respiratory care, chronic therapies, generics, and specialty medicines, giving it a diversified business model across domestic and international markets. Its long-standing position in respiratory treatments, particularly in inhalation therapies, is an important competitive strength, while its US business provides opportunities for growth through generic and specialty pharmaceutical products. Key fundamental factors to monitor include quarterly revenue and profit growth, operating margins, new product launches, regulatory approvals, US FDA observations at manufacturing facilities, pricing pressure in the US generics market, and competition from other pharmaceutical companies.
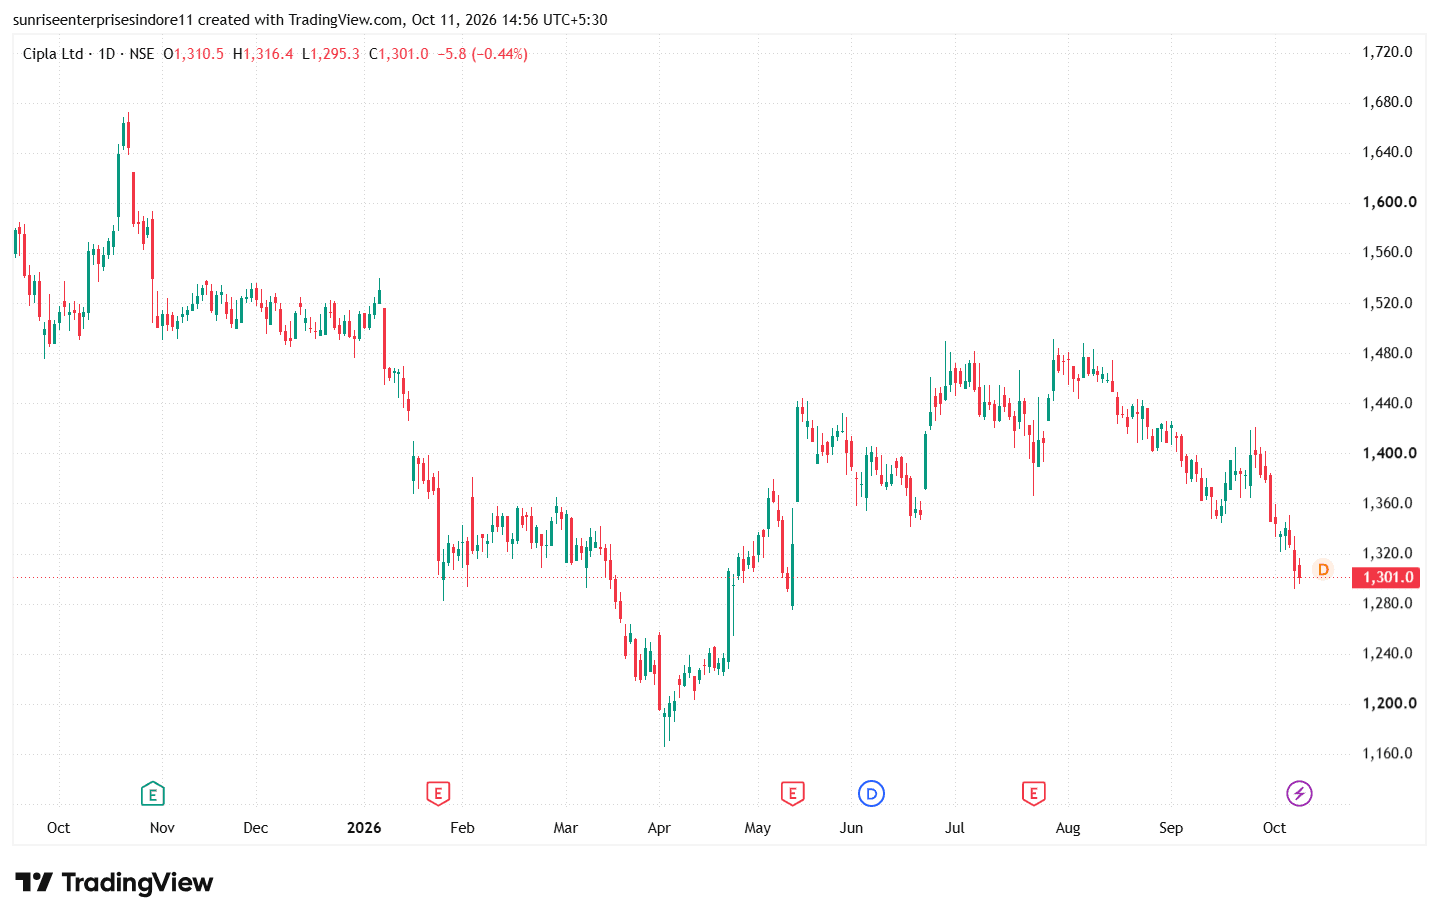
In its latest reported quarter, Q1 FY27, Cipla recorded consolidated revenue of approximately ₹7,119 crore, up 2.3% year-on-year, while net profit declined around 39.2% to ₹789 crore, highlighting pressure on profitability despite modest revenue growth.
The key positive triggers include growth in the Indian pharmaceutical business, respiratory product demand, and potential benefits from new product launches and partnerships; however, recovery in US sales and improvement in profit margins remain important factors to watch.
Overall, Cipla has an established pharmaceutical business and long-term growth opportunities, but investors should monitor upcoming quarterly results, regulatory developments, and valuation before drawing conclusions about the stock's outlook. This analysis is for educational purposes only, not investment advice.