18th Nov · SEBI Registration INH000022729
SEBI Registration INH000022729 · 18th Nov
Profit growth remains positive, but margin pressure
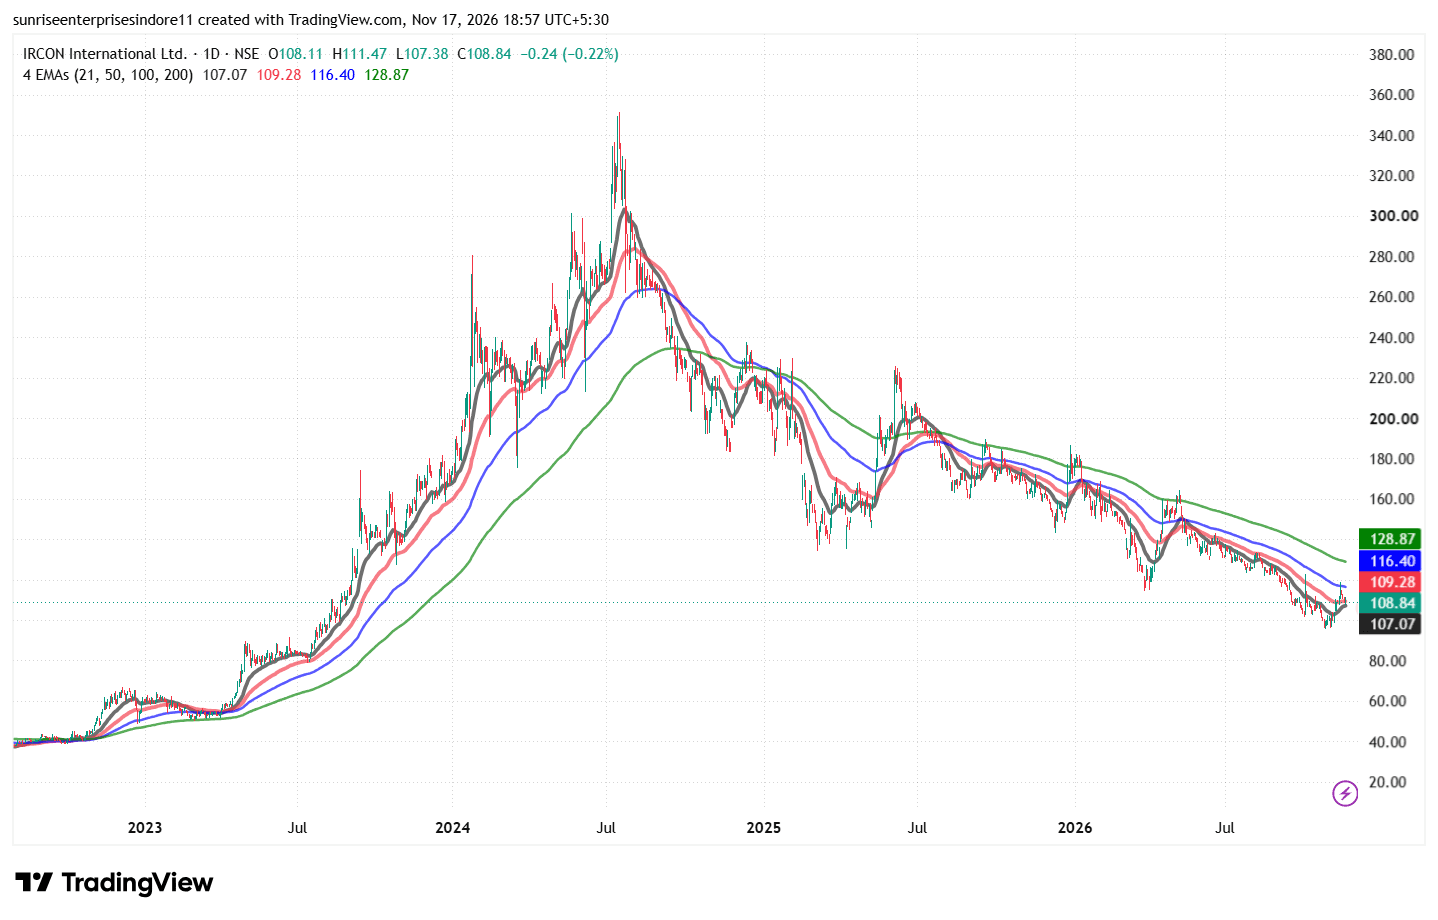
IRCON Railway stocks such as IRCON, RVNL, IRFC, RailTel, RITES, IRCTC and Titagarh Rail Systems have been facing significant selling pressure despite the government's strong railway infrastructure spending. The major reasons are valuation correction after the massive rally in 2023–24, slowing earnings growth, margin pressure on competitive projects, delays in project execution and concerns over fresh order inflows. Importantly, railway capital expenditure has not collapsed; the market is questioning how effectively companies are converting large order books into revenue and profits. Broader market weakness and foreign institutional investor selling have added further pressure. IRCON announced its Q2 FY27 results on 4 November 2026. Consolidated revenue from operations increased 14.9% YoY to ₹2,271.7 crore, while EBITDA increased 7.6% to ₹319.5 crore. However, consolidated net profit declined 26.5% to ₹100.3 crore compared with ₹136.5 crore in the corresponding quarter last year. The bigger concern is its H1 performance, where net profit declined 36% to ₹192.4 crore. Its order book stood at approximately ₹21,296 crore as of September 2026, with 76% exposure to railways. Another concern is that fresh order inflows have been relatively weak compared with project execution, creating questions about future revenue visibility. Although execution is improving on projects such as Sivok–Rangpo and the bullet train, investors are waiting for stronger order inflows and sustainable profit growth before assigning higher valuations RVNL: Large order book, but execution speed and relatively thin operating margins remain concerns. IRFC: Profit growth remains positive, but margin pressure and valuation expectations are important factors. RailTel: Growth expectations and competition in telecom and IT projects are affecting sentiment.