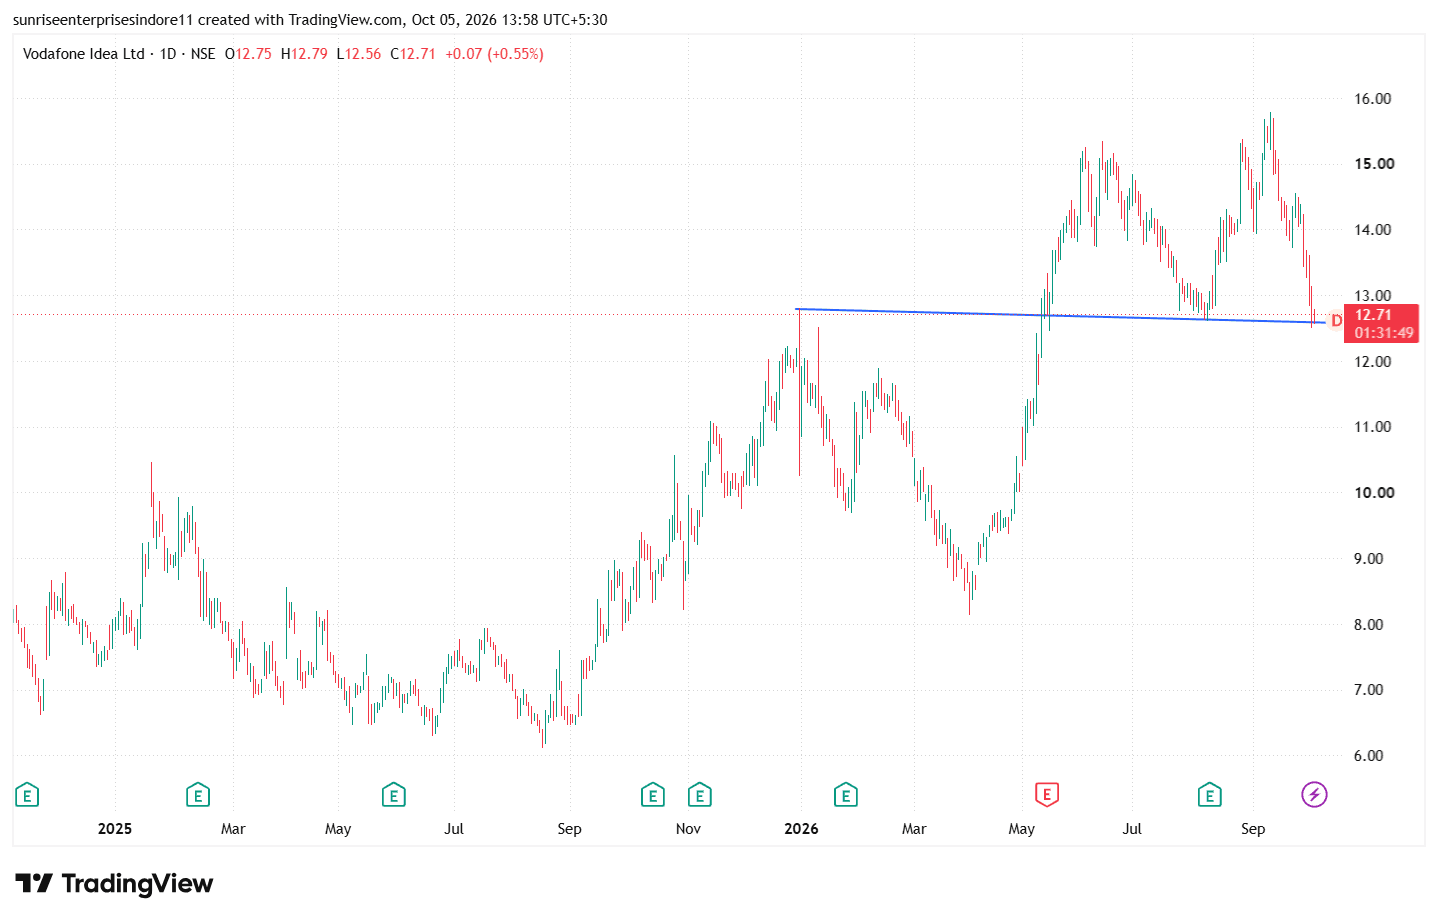
Vodafone Idea (Vi), the latest fundamental picture
IDEA
Vodafone Idea (Vi), the latest fundamental picture is improving operationally but still high-risk financially. The biggest positive is the ₹23,649 crore AGR relief, which reduced the company’s assessed AGR liability to about ₹64,046 crore and extended the major payment burden, significantly improving near-term cash-flow visibility. Vi is now moving aggressively toward network expansion: the company has placed around ₹9,000 crore of capex orders, while management is working on a large ₹35,000 crore bank-funding facility to finance network capex. Operationally, there are early signs of recovery—Vi recorded its first net subscriber additions since the Vodafone-Idea merger, and August 2026 marked the seventh consecutive month of subscriber additions, although its growth remains much slower than Jio and Airtel. Management is also targeting repayment of roughly ₹49,000 crore of spectrum dues over the next three years, supported by higher EBITDA, cash flows and funding. The major positive catalyst going forward would be successful bank funding + continued 5G rollout + tariff hikes/ARPU improvement + sustained subscriber growth. However, the stock remains speculative because Vi still has a very large overall liability burden, weak active-subscriber share versus Airtel/Jio, and substantial future spectrum payments. Overall, AGR relief and improving subscriber trends are bullish for the stock, but execution, funding and cash-flow generation will determine whether this recovery becomes sustainable.