BSE FY26 profit rises 88% to Rs 2,487 crore
BSE Limited reported FY26 consolidated profit of Rs 2,487.25 crore, up 88 percent, on revenue from operations of Rs 4,833.95 crore, up 63 percent. The board approved the results on 7 May and recommended a final dividend of Rs 10 a share.
FY26 numbers (consolidated, company results of 7 May):
Revenue from operations: Rs 4,833.95 crore, up 63 percent from Rs 2,957.34 crore
Net profit: Rs 2,487.25 crore, up 88 percent from Rs 1,322.32 crore
Q4 FY26 net profit: Rs 795.47 crore, up 61 percent from Rs 493.67 crore
Final dividend: Rs 10 a share, record date 10 July 2026
Profit grew faster than revenue. The number to check now is the Q4 FY26 run rate of Rs 795 crore against the Rs 873 crore of Q1 FY27 covered in my 10 October post.
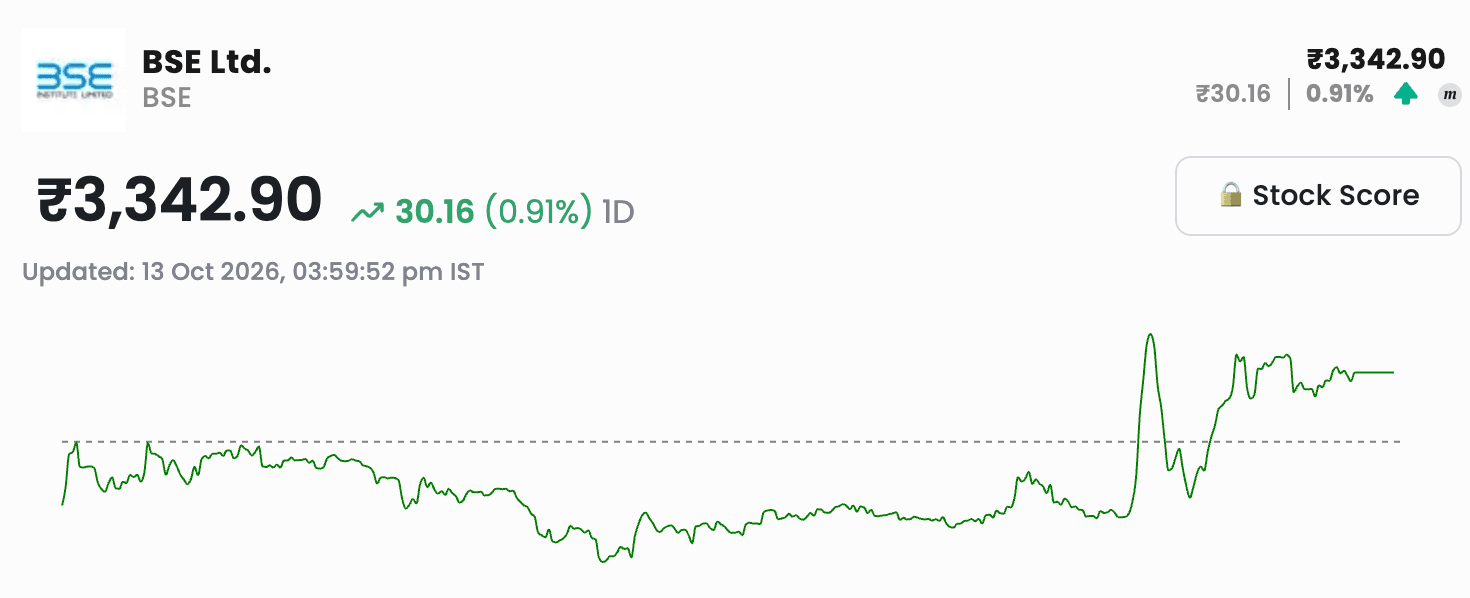
BSE [][***** shares closed at Rs 3,342.90 on 13 October on StockGro, up 0.9 percent on the day. The NSE close on 12 October was Rs 3,330.20. The NSE 52-week range is Rs 2,230.00 to Rs 4,446.80. At 48 times trailing earnings, the market value is 54.6 times FY26 profit, so the price needs the run rate to hold. The Rs 10 dividend yields 0.3 percent at this price.
My view: hold, not a fresh entry. Earnings in this business follow trading volumes, and the market value already assumes they hold. The FY26 result is strong, but the dividend is small. I need Q2 FY27 profit above Q1’s Rs 873 crore. Without that, no fresh money. The dividend does not change the stance.
My exit is a close below Rs 3,075, the 30 September intraday low used in my 10 October post. I watch the Q2 result, due by 14 November under SEBI’s 45-day limit.
Disclosure: Vijay Kumar Gupta, SEBI Registered Research Analyst, INH000020226, Vijay Gupta Advisory. SEBI registration and NISM certification do not guarantee performance or assure returns. Securities markets are subject to market risks. No holdings in the subject company.
#EquityResearch#Miscellaneous#MacroViews#SectorBreakouts#TrendingSectors

 Equity Research
 Fundamental Views
 Hidden Gems
 Index Strategies
 International Market
 IPO
 Macro Views
 Miscellaneous
 Personal Finance
 Post-Closing Commentary
 Pre-Opening Commentary
 Psychology of Money
 Sector Breakout
 Stock In News
 Technical Views
 Time To Exit
 Today's Trading Setup
 Trending Sectors
 US Market
 Watch Out For