5 mins ago · SEBI Registration INH000020226
SEBI Registration INH000020226 · 5 mins ago
CCL Products Q2 FY27 profit up 29%, operating profit 7.6%
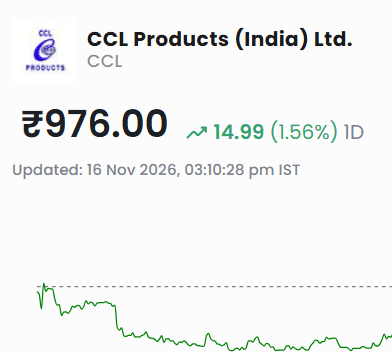
CCL CCL Products (India) Limited reported Q2 FY27 consolidated profit of Rs 130.1 crore, up 29 percent, on revenue up 7.5 percent to Rs 1,210.8 crore. Q2 FY27 numbers (consolidated): Revenue: Rs 1,210.8 crore, up 7.5 percent from Rs 1,126.7 crore Operating profit: Rs 212.1 crore, up 7.6 percent; margin about 17.5 percent, unchanged Profit before tax: Rs 150.9 crore, up 18.7 percent PAT: Rs 130.1 crore, up 29 percent from Rs 100.9 crore Why it matters: PAT grew nearly four times as fast as operating profit. PBT rose 18.7 percent, and the rest of the gap sits below PBT, unexplained in the sources. Operating profit is the cleaner read of the business. CCL Products [CCL][***** traded at Rs 976.88 at 3:09 PM IST on 16 November on StockGro, up 1.65 percent. It is down 10.3 percent over one month and 9.2 percent over one year, and about 21 percent below its 52-week high of Rs 1,231.03. P/E is 28.2 against a sector P/E of 31.1, and P/B is 5.6 against 2.7. My view: hold, not a fresh entry. The headline profit growth rests on lines below operating profit, and operating profit grew 7.6 percent. A P/E of 28 on that base is not cheap, and a P/B of 5.6 against a sector 2.7 puts a premium on the book. Holders can keep the position. Fresh money waits for the Q3 FY27 result (date not confirmed) showing operating profit growing at least as fast as PAT, with a clear explanation of the tax line. Invalidation: a close below Rs 870.37, the 52-week low, which would show the price losing its base. What would change my mind: operating profit growth above 15 percent with the margin holding. Disclosure: Vijay Kumar Gupta, SEBI Registered Research Analyst, INH000020226, Vijay Gupta Advisory. SEBI registration and NISM certification do not guarantee performance or assure returns. Securities markets are subject to market risks. No holdings in the subject company.