Coforge Q2 FY27 profit up 56.5%, EBIT margin at 16%
Coforge Limited reported consolidated Q2 FY27 results on 23 October. EBIT margin reached 16.0 percent, my 4 October test for fresh money.
Q2 FY27 numbers (consolidated):
Revenue: Rs 6,170.8 crore, up 53.6% YoY from Rs 4,016.4 crore
EBITDA: Rs 1,269.7 crore; margin 20.6%
EBIT: Rs 984.7 crore, up 67.8% YoY; margin 16.0%
PAT: Rs 588.1 crore, up 56.5% YoY
Order intake US$1.04 billion; executable order book US$2.38 billion, up 45%
This was the first full quarter with Encora, bought on 23 April. Organic constant-currency growth was 3.8 percent QoQ out of 10.9 percent reported. Management raised the FY27 EBIT margin guide to 16 percent from 15.5 percent and targets 17 percent in Q4. Shares fell to Rs 1,814.35 on 26 October from a Rs 1,900 close, then recovered.
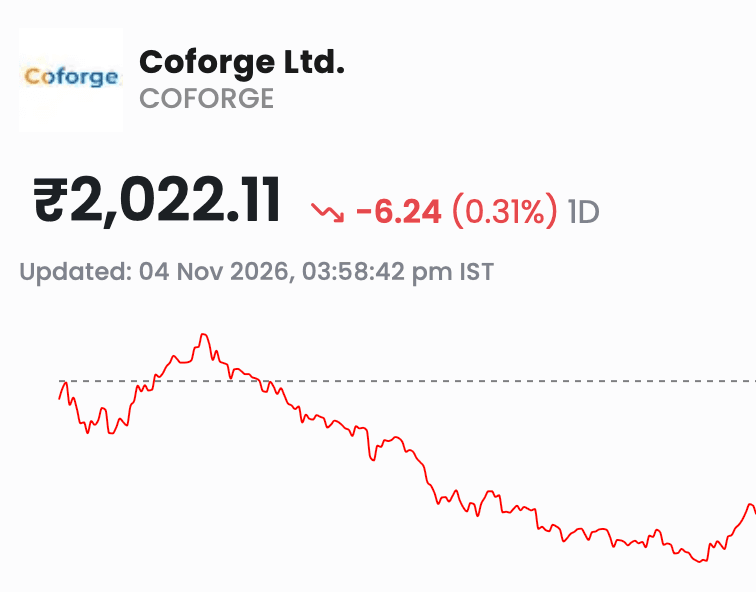
Coforge [][***** shares closed at Rs 2,022.11 on 4 November on StockGro (NSE Rs 2,060.00), up 11.0 percent in a month, 2.5 percent below the NSE 52-week high of Rs 2,112.20. P/E 39.9; sector near 21.
My view: hold, not a fresh entry at this price. My 4 October gate was a full Encora quarter, a 16 percent EBIT margin and no further board exit. All three are met. But that gate pointed to Rs 1,780 to 1,810, and the stock is 14 percent above it. At about 39 times Q2 run-rate profit, the price already assumes the 17 percent Q4 margin, while organic growth is 3.8 percent. Holders stay; exit on an NSE close below Rs 1,814.35, the results-day low, or a Q3 EBIT margin under 16 percent. Fresh money waits for a pullback towards Rs 1,900, the pre-results close. Next trigger: Q3 FY27, with eight or more large deals expected.
Disclosure: Vijay Kumar Gupta, SEBI Registered Research Analyst, INH000020226, Vijay Gupta Advisory. SEBI registration and NISM certification do not guarantee performance or assure returns. Securities markets are subject to market risks. No holdings in the subject company.
#MacroViews#Miscellaneous#PsychologyofMoney#EquityResearch#TrendingSectors

 Equity Research
 Fundamental Views
 Hidden Gems
 Index Strategies
 International Market
 IPO
 Macro Views
 Miscellaneous
 Personal Finance
 Post-Closing Commentary
 Pre-Opening Commentary
 Psychology of Money
 Sector Breakout
 Stock In News
 Technical Views
 Time To Exit
 Today's Trading Setup
 Trending Sectors
 US Market
 Watch Out For