Hero MotoCorp September sales rise 11.5%; scooters up 64.5%
Hero MotoCorp Limited dispatched 7,66,348 two-wheelers in September 2026, up 11.5 percent YoY from 6,87,220 units, according to its 1 October release. Domestic dispatches were 7,39,018 units, up 14.1 percent.
September 2026 dispatches (units):
Motorcycles: 6,65,994, up 6.4 percent YoY
Scooters: 1,00,354, up 64.5 percent YoY
Exports: 27,330, down 31.1 percent YoY
Q1 FY27: revenue Rs 12,999 crore, up 36 percent; net profit Rs 1,454 crore, up 29 percent; volume up 23 percent. The EBITDA margin was 13.3 percent, about 1 point lower than a year earlier on my derivation.
Scooters carried the month. Motorcycles, where most profit sits, grew 6.4 percent.
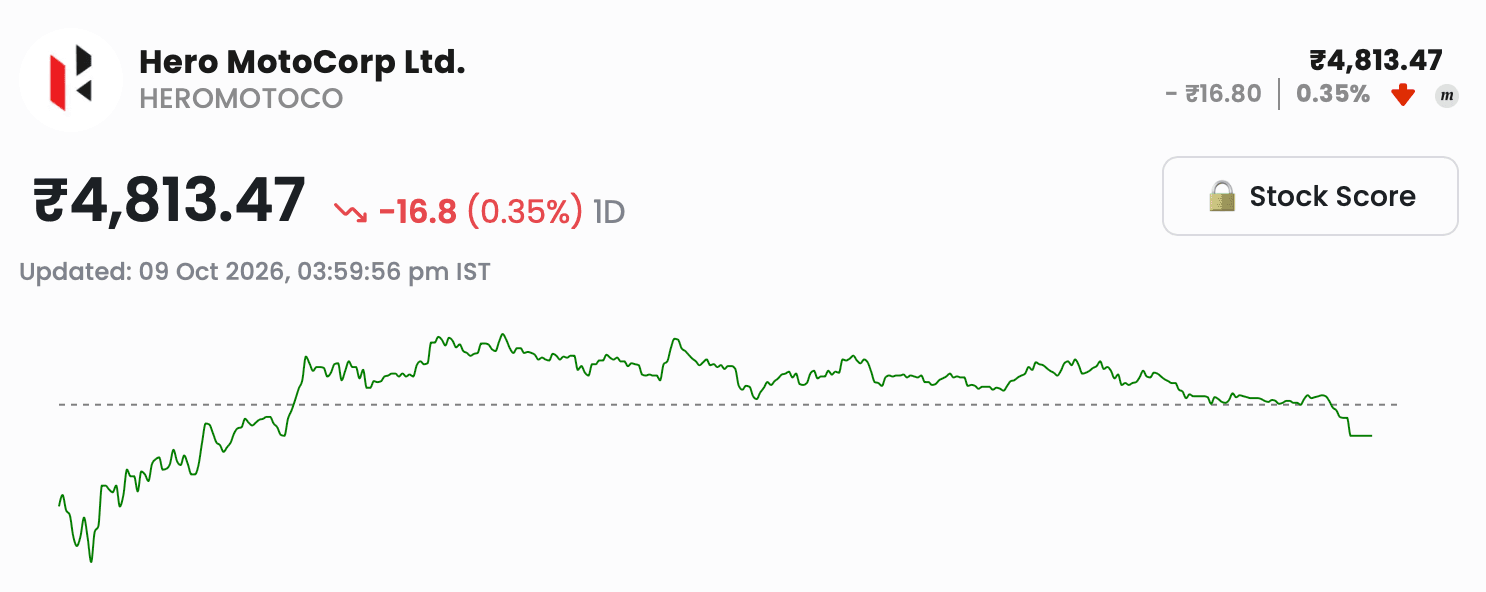
Hero MotoCorp [][***** shares closed at Rs 4,813.47 on 9 October on StockGro (NSE Rs 4,895.50), up 0.8 percent on the NSE that day. The NSE price is 4.8 percent above the 52-week low of Rs 4,671.50 and 23.4 percent below the high of Rs 6,388.50. At 17.7 to 17.8 times trailing earnings, it is down 10 percent over a year.
My view: hold for holders, no fresh money yet. Volume came from scooters, not motorcycles. Exports fell 31 percent, a weaker overseas book. Q1 profit grew 29 percent, but the margin fell. I want two things in Q2 FY27: motorcycle dispatches growing faster than 6.4 percent, and EBITDA margin back near 14.4 percent, the Q1 FY26 level I derived. Without both, no fresh money.
My exit is a close below Rs 4,671.50, the NSE 52-week low. I watch the Q2 FY27 result, date unconfirmed, and the October sales release.
Disclosure: Vijay Kumar Gupta, SEBI Registered Research Analyst, INH000020226, Vijay Gupta Advisory. SEBI registration and NISM certification do not guarantee performance or assure returns. Securities markets are subject to market risks. No holdings in the subject company.
#FundamentalViews#TechnicalViews#Today’sTradingSetup#StockInNews#WatchOutFor

 Equity Research
 Fundamental Views
 Hidden Gems
 Index Strategies
 International Market
 IPO
 Macro Views
 Miscellaneous
 Personal Finance
 Post-Closing Commentary
 Pre-Opening Commentary
 Psychology of Money
 Sector Breakout
 Stock In News
 Technical Views
 Time To Exit
 Today's Trading Setup
 Trending Sectors
 US Market
 Watch Out For