Hindustan Zinc H1 output record; Q1 profit was a price peak
Hindustan Zinc Limited reported its highest-ever first-half refined metal output on 3 October. Mined metal for the half was 539 kt, up 3 percent YoY, and silver output was 321 tonnes, up 10 percent.
Q2 FY27 operating update (company, 3 October):
Mined metal: 271 kt, up 5 percent YoY
Refined metal: 264 kt, up 7 percent YoY
Silver: 173 tonnes, up 20 percent YoY
Wind power: 155 million units, up 17 percent YoY
Volume is growing, but the profit is not a volume story. Q1 FY27 consolidated PAT was Rs 5,469 crore, up 145 percent, on revenue of Rs 13,747 crore. Q1 silver output was flat at 149 tonnes, and silver prices moderated sequentially, so the jump came from price.
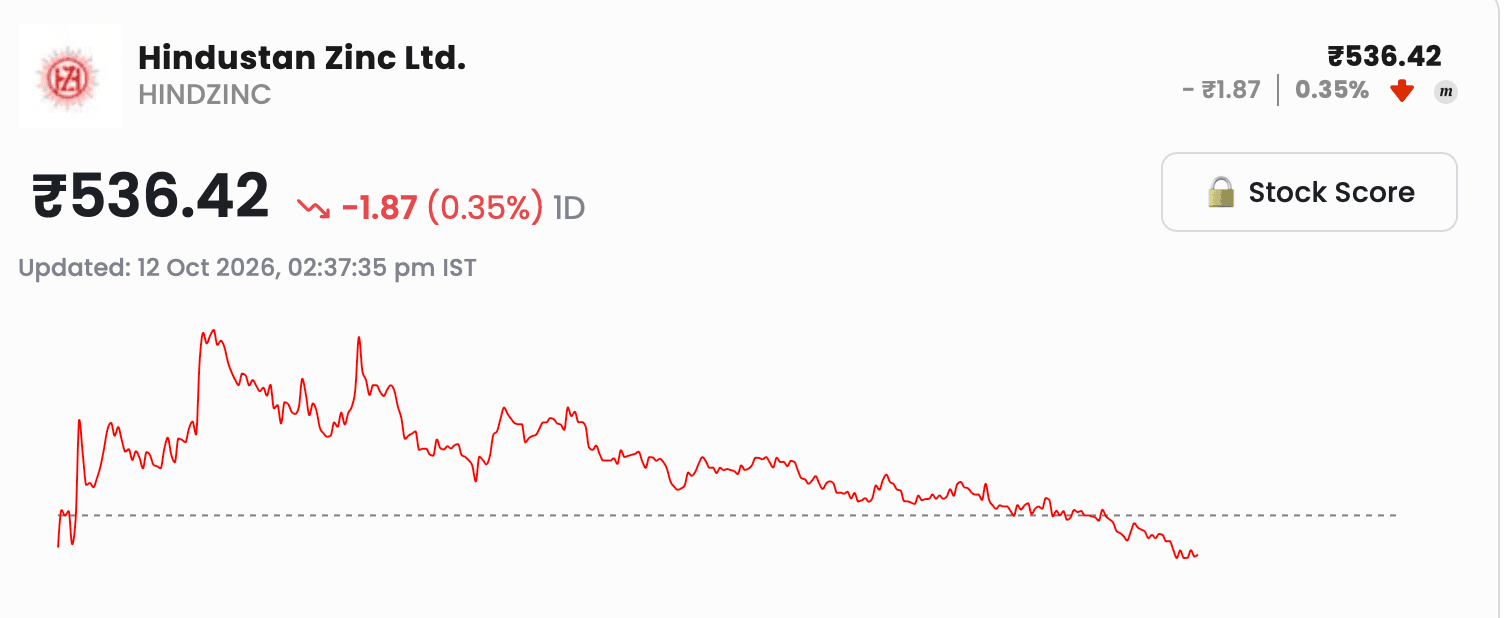
Hindustan Zinc [][***** trades at Rs 536.77 at 2:36 PM IST today on StockGro, down 0.3 percent. The NSE close on 9 October was Rs 543.50, and the NSE 52-week range is Rs 453.50 to Rs 733.00. At 13.3 to 13.5 times trailing earnings, against a sector P/E near 11, the stock is not cheap for a metal producer.
My view: hold, not a fresh entry. Refined output and silver both rose faster than a year ago, and that is real. But trailing earnings include a record quarter, and the P/E is only as cheap as Q1 is repeatable. I need Q2 FY27 PAT at or above the Rs 5,469 crore of Q1, silver output at or above the 173 tonnes of Q2, and the result date confirmed. Without all three, no fresh money.
My exit is a close below Rs 453.50, the NSE 52-week low. I watch the Q2 result and the silver price.
Disclosure: Vijay Kumar Gupta, SEBI Registered Research Analyst, INH000020226, Vijay Gupta Advisory. SEBI registration and NISM certification do not guarantee performance or assure returns. Securities markets are subject to market risks. No holdings in the subject company.
#MacroViews#EquityResearch#PsychologyofMoney#Miscellaneous#HiddenGems

 Equity Research
 Fundamental Views
 Hidden Gems
 Index Strategies
 International Market
 IPO
 Macro Views
 Miscellaneous
 Personal Finance
 Post-Closing Commentary
 Pre-Opening Commentary
 Psychology of Money
 Sector Breakout
 Stock In News
 Technical Views
 Time To Exit
 Today's Trading Setup
 Trending Sectors
 US Market
 Watch Out For