Wipro Limited is one of eight companies the US Labor Department suspended from its Permanent Labor Certification (PERM) programme on 8 October. It will not accept new or pending PERM applications involving Wipro. Existing H-1B visas are not cancelled.
Q1 FY27 numbers (consolidated, 16 July):
Revenue: Rs 24,479 crore, up 10.6 percent YoY
Net profit: Rs 3,352 crore, up 0.6 percent YoY from Rs 3,330 crore
IT services operating margin: 16 percent, down 130 basis points QoQ
Q2 FY27 guide: IT services revenue down 1.5 to up 0.5 percent QoQ
The margin fell in June and the September guide is flat to down, so there is little room to absorb a cost. Aggregator PERM counts (611 filings in 2023, 569 in 2022) lack 2024 and 2025 rows, so the pending cases cannot be sized.
Wipro [
WIPRO
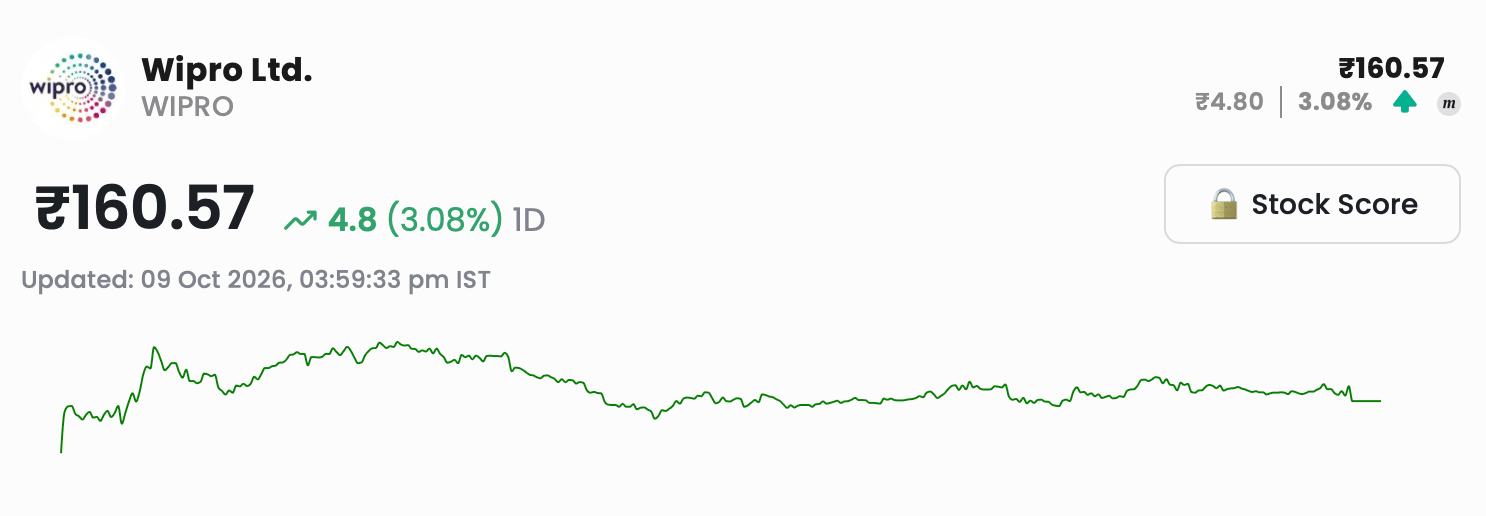
][***** shares closed at Rs 160.57 on 9 October on StockGro (NSE Rs 162.57), up 2.65 percent. It sits 3.7 percent above the NSE 52-week low. At 11.8 to 12.6 times trailing earnings, the price already reflects weak growth.
My view: hold, not a fresh entry. My 2 October stance was hold until a margin recovery plan emerges, and the suspension adds a cost line before any plan can show. I accept the 9 October reports that the immediate effect is limited. The gate is the 15 October result, released after market hours. I need the Q2 margin near 16 percent and a PERM count or cost estimate. Without both, no fresh money.
My exit is a close below Rs 156.79, the NSE 52-week low. Resistance is Rs 177.74, the close on Q1 results day. I watch the 15 October result and any Labor Department statement on the suspension’s length.
Disclosure: Vijay Kumar Gupta, SEBI Registered Research Analyst, INH000020226, Vijay Gupta Advisory. SEBI registration and NISM certification do not guarantee performance or assure returns. Securities markets are subject to market risks. No holdings in the subject company.