sugar, ethanol/alcohol, co-generation power and bagasse.
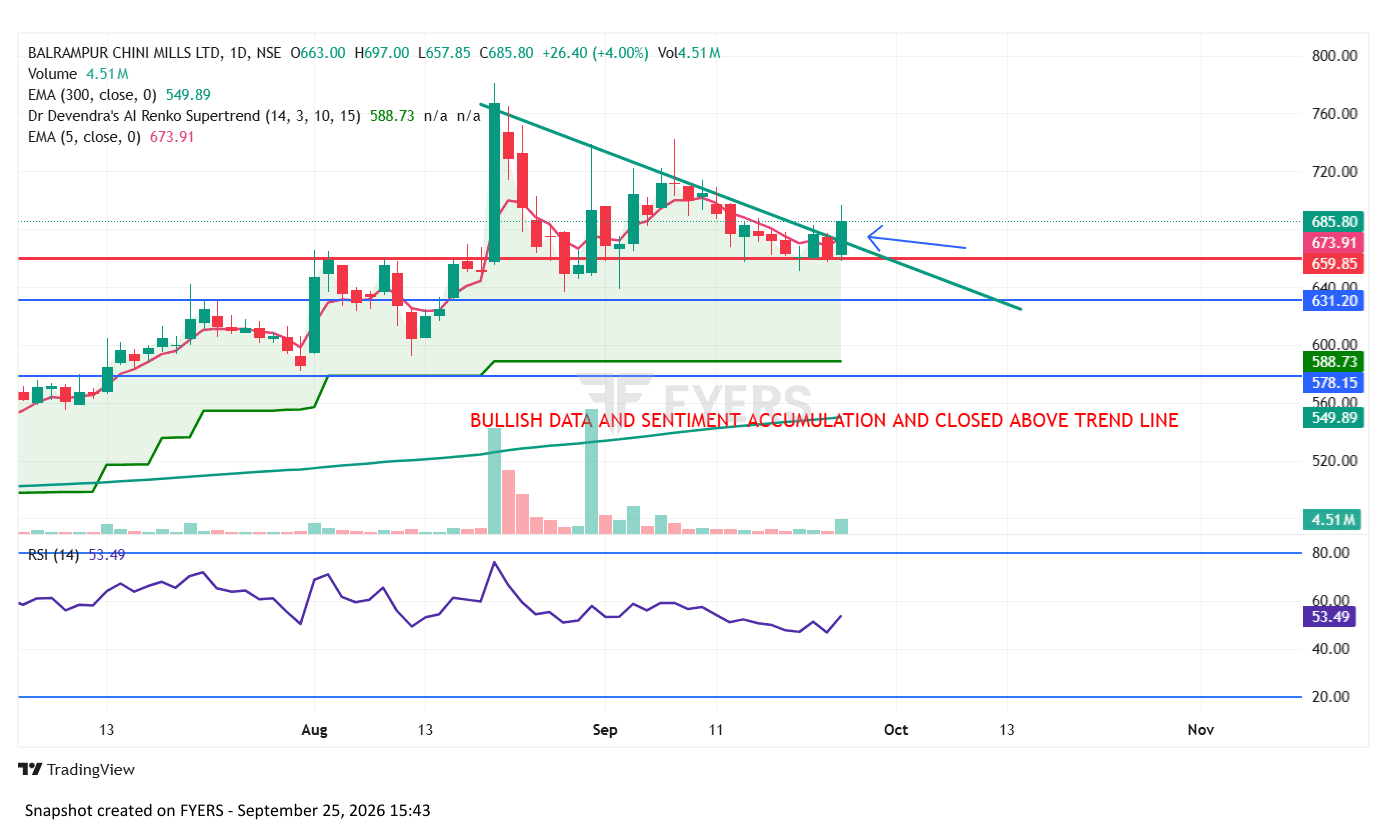
BALRAMCHIN
Strengths
Large integrated sugar manufacturing platform with significant scale.
Diversified revenue streams from sugar, ethanol, power and downstream products.
Strong farmer network and established cane procurement ecosystem.
Ethanol provides diversification away from dependence on sugar alone.
FY26 consolidated revenue from operations was approximately ₹6,271 Cr, with consolidated net profit of about ₹378 Cr.
Weaknesses
Sugar remains a cyclical business and profitability can vary significantly between sugar seasons.
Performance is sensitive to cane prices, sugar realisations and recovery rates.
Government policies significantly influence sugar exports, ethanol allocation and pricing.
Working-capital requirements can increase during the sugarcane crushing season.
PLA project involves significant capital expenditure and execution/ramp-up risk.
Opportunities
India's increasing ethanol-blending requirement can support long-term demand for ethanol.
Expansion of ethanol/distillery capacity can improve the company's business mix.
PLA manufacturing could provide exposure to biodegradable/compostable material demand.
Higher sugar realisations can improve cash generation during favourable cycles.
Co-generation and sale of surplus power provide an additional revenue stream.
Threats
Adverse government policy on sugar exports, domestic inventory or ethanol pricing.
Higher sugarcane procurement costs can compress margins.
Weak sugar prices or lower recovery rates.
Weather events, drought, excess rainfall and pest/disease can affect cane availability.
Competition from other integrated sugar and ethanol producers.
Execution and commercialisation risks associated with the PLA project.
Commodity and energy-price volatility.