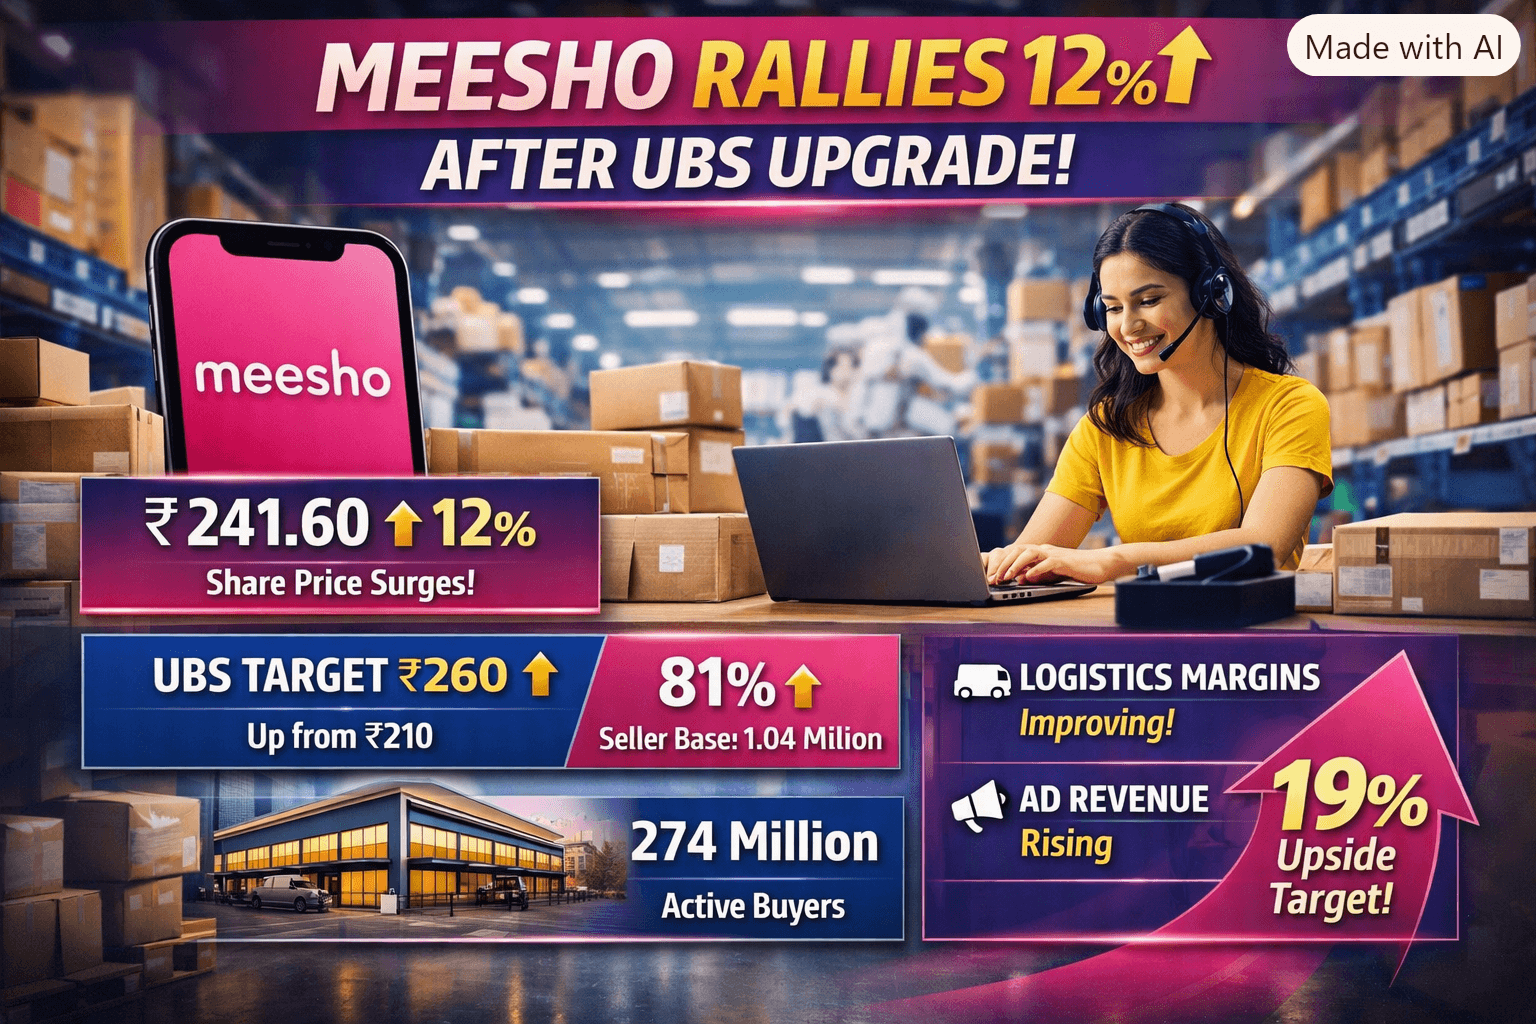
Meesho shares surged nearly 12% on September 22, 2026, after UBS raised its target price to ₹260, citing stronger growth in sellers, buyers, and improving margins. Despite continued quarterly losses, analysts remain bullish on Meesho’s long-term profitability and logistics efficiency.
📈 Market Highlights
Share Price: ₹241.60 on NSE, up 10.24% intraday.
UBS Target Price: Raised from ₹210 → ₹260, implying ~19% upside.
Brokerage View: UBS maintained a “Buy” rating, projecting 25% NMV CAGR (FY26–31).
Investor Sentiment: Strong momentum after UBS revision; Meesho among top midcap gainers.
💰 Q2 FY26–27 Financial Performance
Metric Q2 FY26–27 QoQ Change YoY Change Remarks
Revenue ₹3,073.67 crore ▼22.76% ▲48.28% Growth driven by higher order volumes
Operating Profit ₹–483.32 crore ▼43.18% Improved sequentially
Net Profit (Loss) ₹–411.36 crore ▼42.16% Loss narrowing trend continues
Operating Margin –15.72% — — Reflects reinvestment in logistics & ads
EPS –₹0.85 ▼66.66% — Negative but improving trajectory
🚀 Growth Drivers
Seller Base: Up 81% YoY to 1.04 million in Q1 FY27.
Buyer Base: Up 29% YoY to 274 million active users.
Advertising Revenue: Crossed 3% of NMV, expected to double by FY28.
Logistics Cost: Declined from ₹44 to ₹42 per parcel; margins expected to recover to 2.5% in 2–3 quarters.
AI Integration: Meesho’s Valmo platform helping 10,000 delivery partners file tax returns — part of its tech-driven ecosystem.
🧭 Analyst Outlook
UBS: Expects EBITDA growth of 20–40% over FY29–31.
Management Guidance: Confident of low-30s NMV growth for FY27 despite seasonal Diwali shift.
User Retention: 50–55% of new users are organic; 18-month payback on acquisition costs.
Long-Term Goal: 500 million annual transacting users (ATUs) by FY31.