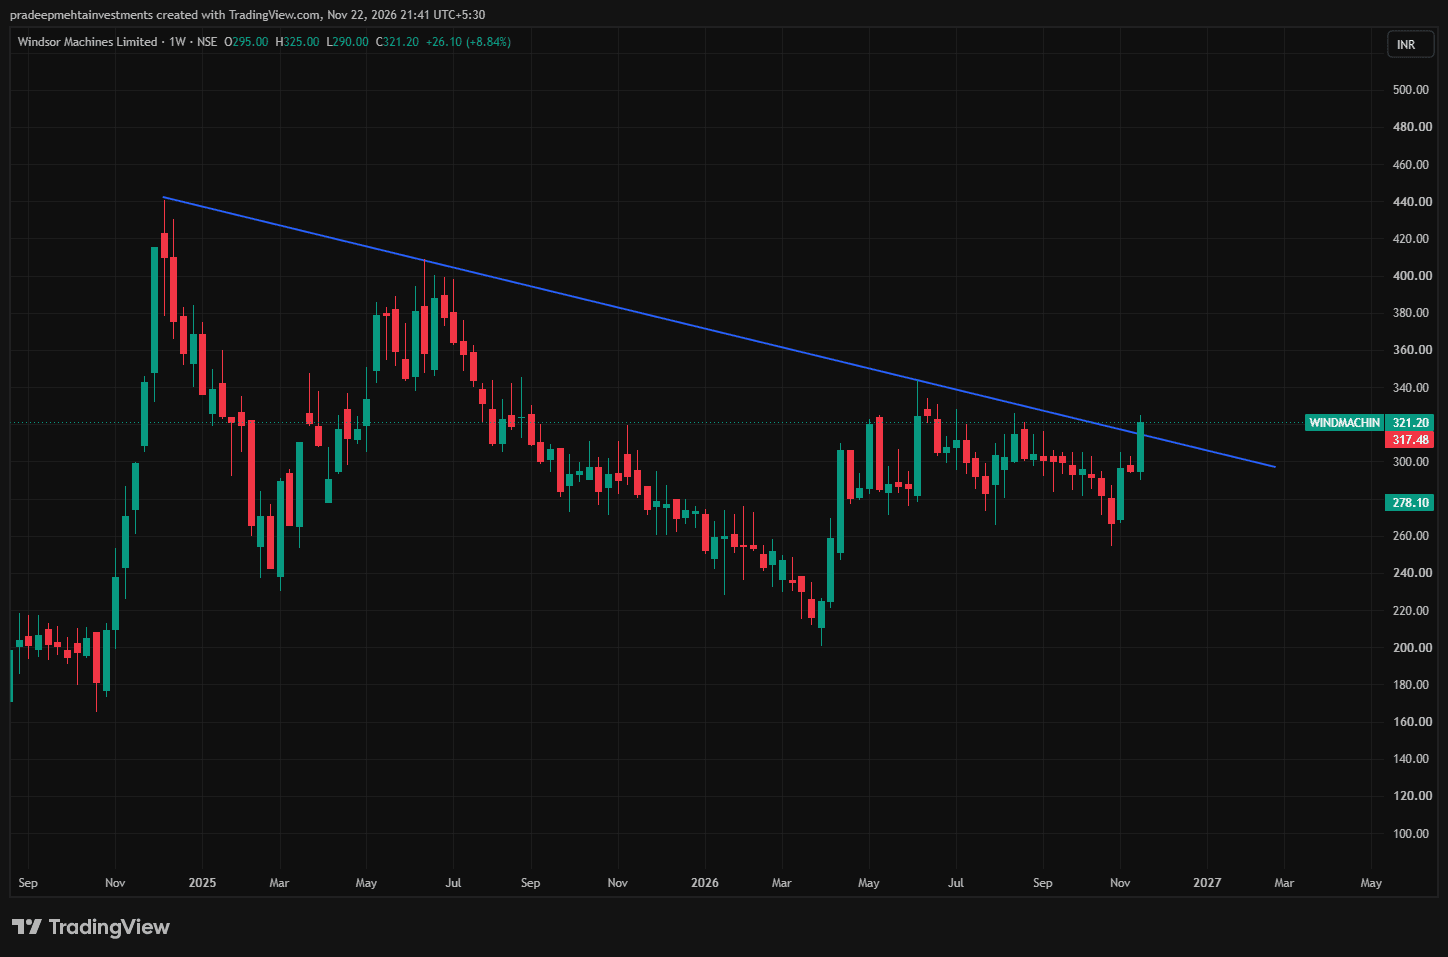
Business expansion and order book growth in focus
WINDMACHIN Business expansion and order book growth in focus **WINDMACHIN** Windsor Machines: Strong revenue growth, expanding order book and proposed fundraise highlight the company's growth plans. Windsor Machines Limited (NSE: WINDMACHIN) is an Indian engineering company engaged in manufacturing plastic processing machinery, including injection moulding machines, extrusion machinery, blown-film lines and CNC machines. The company serves customers across domestic and international markets. **Why it matters:** The company reported Q2 FY27 revenue of ₹182.8 crore, up 33.8% year-on-year. Its consolidated order book stood at ₹273 crore as of September 2026, compared with ₹217 crore in June. Additionally, its CNC division secured government tender orders worth ₹59 crore for 38 machines in October 2026. **My view:** Revenue growth and a rising order book indicate improving business activity. The proposed ₹188.12 crore fundraise through convertible warrants could support future business requirements. However, profitability remains a major concern, with Q2 EBITDA at just ₹1.6 crore and an adjusted net loss of ₹5.3 crore. **What to watch:** Order book execution, new government orders, revenue growth, EBITDA margin recovery, working capital requirements, fund utilisation and the company's ability to return to consistent profitability. **Stance:** Windsor Machines offers growth opportunities through increasing demand for industrial machinery, a stronger order book and expansion plans. However, weak margins, continued losses and execution risks remain important considerations. **Disclosure:** I am a SEBI Registered Research Analyst. This content is for educational purposes only and is not a recommendation to buy or sell any security. Investors should conduct their own research or consult a registered financial advisor before making investment decisions.