NYKAA Q2 FY27: Scaling a Consumer Beauty & Fashion Ecosystem
NYKAA
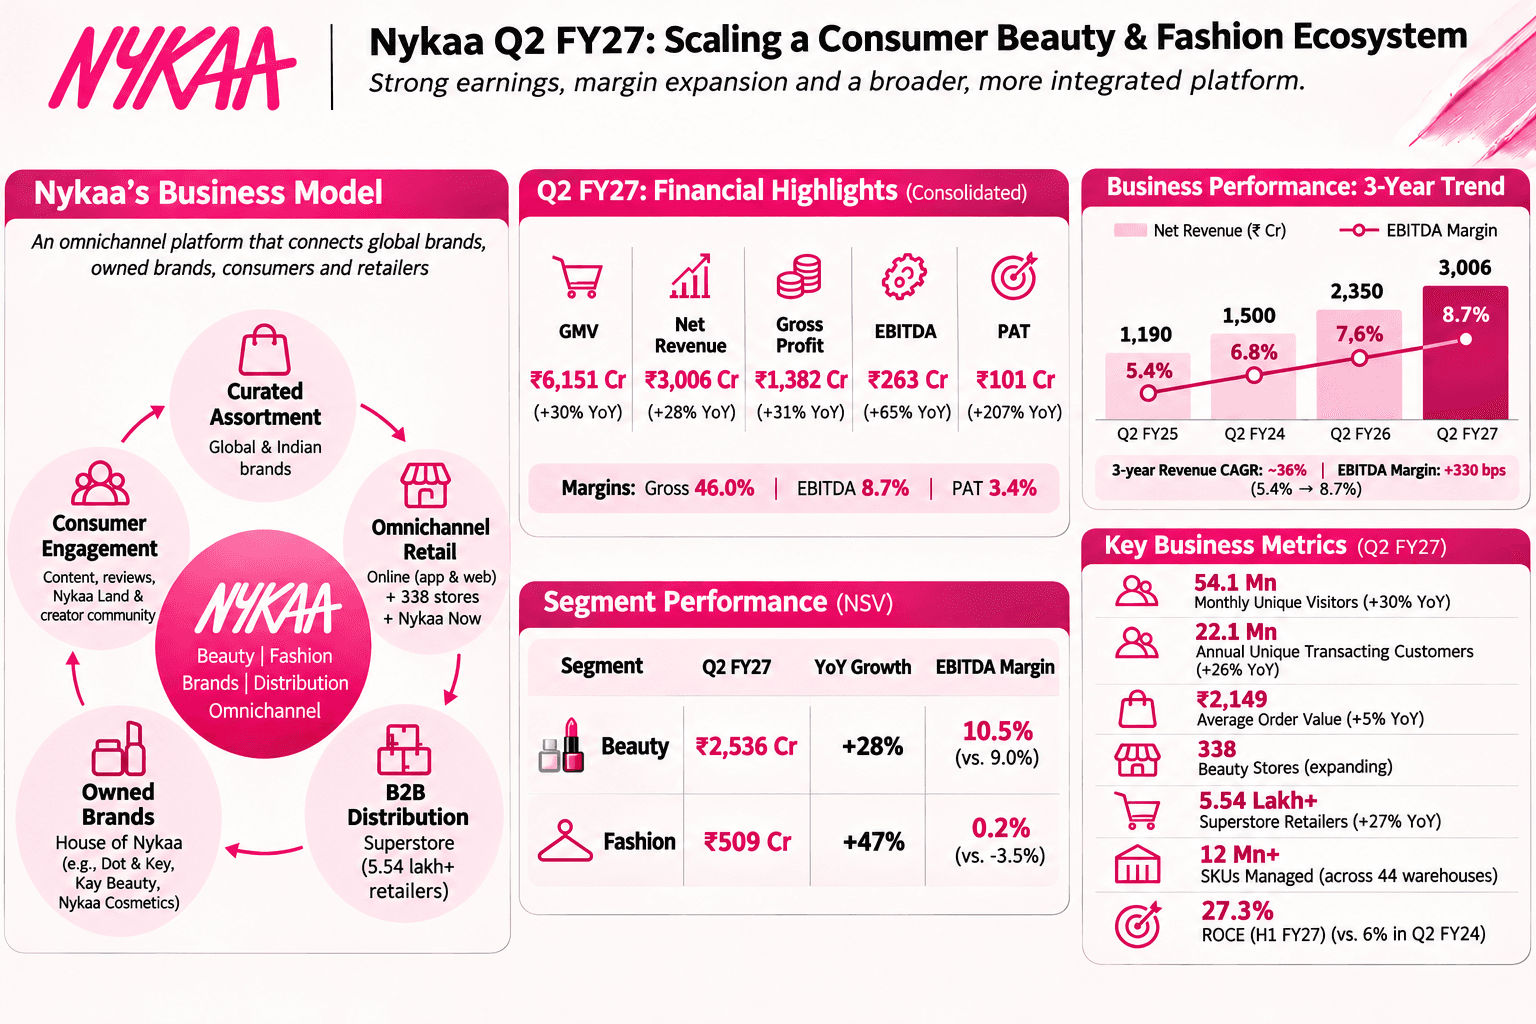
is evolving from an online beauty retailer into an integrated consumer & brand-distribution platform. Growth depends on strengthening Beauty, improving Fashion profitability & scaling newer channels
Beauty: Growth is driven by customer acquisition, premiumisation & repeat engagement. Physical retail remains strong, with like-for-like growth above 20%. Management targets 600 stores over the next few years.
Fashion: Wider assortment, international partnerships & expansion in footwear & men's categories support growth. The segment has reached EBITDA breakeven, but sustainable profitability remains a challenge
Global Store & Superstore: Nykaa is positioning itself as an India market-entry partner for international beauty brands while expanding its B2B retailer network
Nykaa Now: Quick commerce is scaling with a wider beauty assortment & faster delivery, potentially improving purchase frequency. Standalone economics remain undisclosed
Growth Plans:
Margin improvement reflects operating leverage & expense efficiency, with marketing & other operating costs declining as a share of revenue. Fulfilment remains an investment area.
Fashion profitability is a longer-term journey. Management reiterated its ambition of high-single-digit EBITDA margins by FY30 & 10%+ at steady state. This is not a near-term target; progress depends on marketing efficiency, repeat customers & operating leverage include expanding Beauty retail, scaling Nykaa Now & Superstore, onboarding global brands & improving Fashion economics
Investor Takeaway:
H1 operating cash flow was negative due to festive inventory build-up. Management expects normalisation by Q3. Inventory discipline & cash conversion remain key monitorables. Nykaa is building an integrated beauty, fashion & distribution ecosystem. Improving margins & channel expansion are encouraging, but sustainable Fashion profitability, cash flow & execution remain key tests. Valuation will ultimately determine shareholder returns