1 hour ago · SEBI Registration INH000020226
SEBI Registration INH000020226 · 1 hour ago
Coromandel Q2 FY27 profit falls 34% to Rs 523 crore
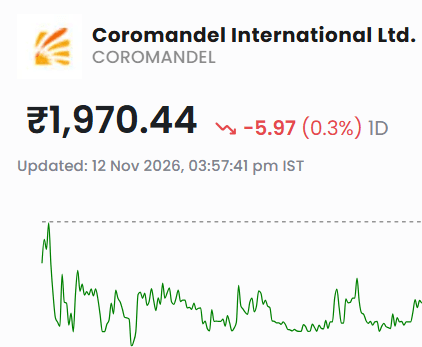
COROMANDEL Coromandel International Limited reported Q2 FY27 consolidated profit of Rs 523 crore, down 34 percent, on revenue up 6 percent to Rs 10,348 crore. Q2 FY27 numbers (consolidated): Revenue: Rs 10,348 crore, up 6 percent YoY EBITDA: Rs 944 crore, down 18 percent YoY; margin about 9.1 percent PAT: Rs 523 crore, down 34 percent from Rs 793 crore Why it matters: the company blamed a sharp rise in raw material costs linked to the Middle East crisis, which subsidies did not fully offset. New NPK fertiliser capacity is due by Q4 FY27, and extra capacity for one crop protection molecule by Q3, so the cost squeeze is the near-term test. Coromandel International [COROMANDEL][***** closed at Rs 1,970.44 on 12 November on StockGro, up 15.75 percent over one month but down 7.11 percent over one year. It is 21 percent below its 52-week high of Rs 2,483.54. P/E is 37.25 against a sector P/E of 29.96. My view: hold, not a fresh entry. The rally has run ahead of earnings. The stock is up 16 percent in a month while profit fell a third, and at 37 times trailing earnings it carries a premium to the sector. The trailing P/E reflects a margin trough. But the company has not yet shown that costs are easing. Holders can keep the position. Fresh money should wait for the Q3 FY27 result (date not confirmed) showing EBITDA margin rising from 9.1 percent, with the NPK capacity on schedule. Invalidation: a close below Rs 1,623.38, the 52-week low, which would mean the price is discounting a longer squeeze than the rally assumes. What would change my mind: a fall in raw material costs. Disclosure: Vijay Kumar Gupta, SEBI Registered Research Analyst, INH000020226, Vijay Gupta Advisory. SEBI registration and NISM certification do not guarantee performance or assure returns. Securities markets are subject to market risks. No holdings in the subject company.