Reliance Q1 profit down 22% YoY as crude base weakens
Reliance Industries Limited reported consolidated Q1 FY27 results on 20 July 2026 with sequential strength masked by a tough prior-year crude base that compressed year-on-year profit 22 percent.
Q1 FY27 numbers (consolidated):
Revenue: Rs 3,09,468 crore, up 25% YoY; +5% QoQ
PAT: Rs 20,946 crore, down 22.4% YoY; up 23% QoQ
EBITDA: Rs 47,517 crore, up 8% QoQ; margin 15.4%
Finance costs: Rs 8,337 crore, up 27% QoQ
O2C revenues jumped 9 percent and EBITDA surged 17 percent. Oil and gas EBITDA climbed 19 percent sequentially on crude strength, but the year-ago quarter rode prices above $85 per barrel. Digital Services EBITDA at Rs 21,255 crore (up 6% QoQ) remains the profit engine. Retail contracted 8 percent revenue. The profit decline reflects both the base and Rs 1,752 crore jump in finance costs amid capital deployment in renewables and 5G.
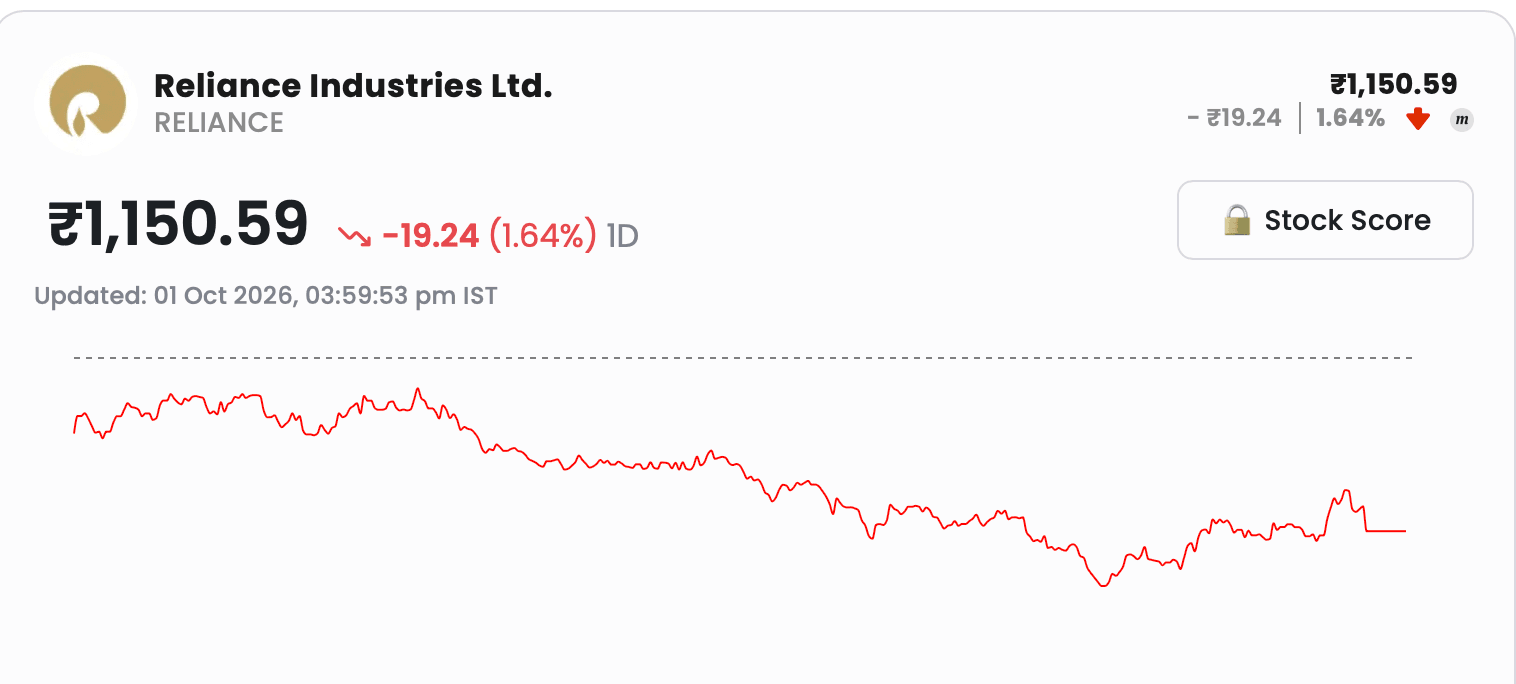
Reliance [] shares closed at Rs 1,150.59 on 1 October on StockGro, ***** (NSE Rs 1,150.59), down 10.7% over one month and 15.9% YoY. 52-week high Rs 1,597; P/E 20.84 versus sector 13.42; market cap Rs 16,60,000 crore.
My view: Hold into Q2 results. Sequential momentum is real, but the stock repriced 16 percent down from August on rate hikes and crude weakness. The 20.84x P/E is expensive to history and peers. Holders wait for Q2 to confirm Digital momentum and Retail stabilisation. Fresh money waits for Rs 1,000 to 1,050 support or crude clarity. Risk: Q2 shows Retail still weak, capex accelerating, net debt rising, or DII outflows continuing. Invalidation: crude below $75. Resistance Rs 1,250; support Rs 1,050.
Disclosure: Vijay Kumar Gupta, SEBI Registered Research Analyst, INH000020226, Vijay Gupta Advisory. SEBI registration and NISM certification do not guarantee performance or assure returns. Securities markets are subject to market risks. No holdings in the subject company.
#StockInNews#PsychologyofMoney#HiddenGems#SectorBreakouts#TechnicalViews

 Equity Research
 Fundamental Views
 Hidden Gems
 Index Strategies
 International Market
 IPO
 Macro Views
 Miscellaneous
 Personal Finance
 Post-Closing Commentary
 Pre-Opening Commentary
 Psychology of Money
 Sector Breakout
 Stock In News
 Technical Views
 Time To Exit
 Today's Trading Setup
 Trending Sectors
 US Market
 Watch Out For