TVS Motor September sales up 24.35%, shares fall 2.07%
TVS Motor Company Limited sold 672,790 units in September, up 24.35 percent from 541,064, and the stock fell 2.07 percent on 1 October, the day the numbers came out.
September numbers:
- Domestic two-wheelers 482,073, up 17%; international 180,700, up 48%
- Electric two-wheelers 65,799, up 110%
- Q2 FY27: about 1.9 million units, up 27%
- Q1 FY27 (21 Jul): EBITDA Rs 1,779 crore, margin 12.8% vs 12.5%; PBT included about Rs 150 crore of fair valuation gains
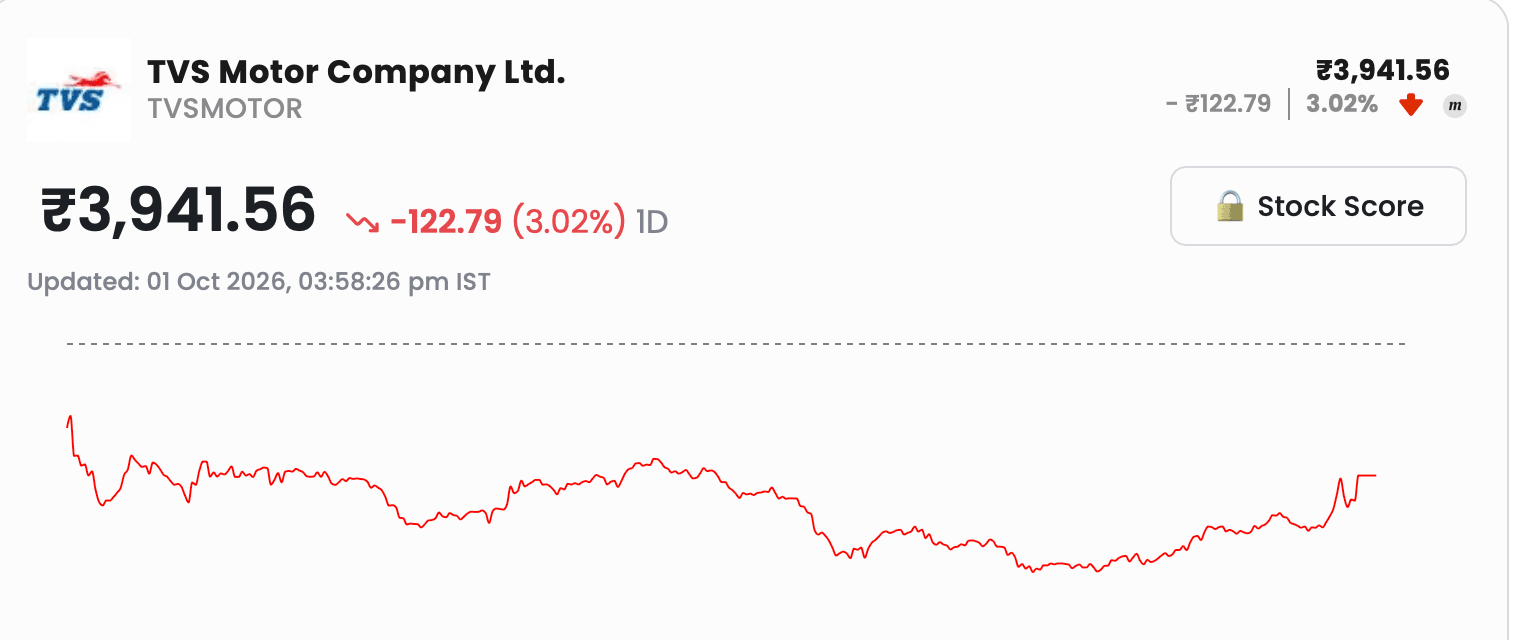
TVS Motor [][***** shares closed at Rs 3,941.56 on 1 October on StockGro (NSE Rs 4,021.00), 10.3 percent below the NSE high of Rs 4,484.50 on 26 August. P/E 54.63; sector P/E 19.69.
My view: hold, not a fresh entry. Demand is not the question: September rose 24 percent and exports 48 percent. The price is. At 54.63 times trailing earnings against a sector near 20, the stock needs margins to hold while costs rise; management absorbed 3.5 percent raw material inflation in Q1 and expects 0.5 percent more in Q2. Q1 profit also carried fair valuation gains, so the EPS base is softer than it looks, and domestic growth of 17 percent means the mix is export-led. Motilal Oswal Wealth's Rs 4,470 target (28 July) is 11 percent above Thursday's close. Holders stay into the Q2 FY27 results; the date is not yet intimated, last year it was 28 October. Fresh money waits for a Q2 EBITDA margin of 12.8 percent or better. Support is Rs 3,974, the 23 July high; resistance Rs 4,156, the level Vivek Kumar saw it clear on 27 September. My exit is a close below Rs 3,930, the 1 October low, or a Q2 margin under 12.5 percent.
Disclosure: Vijay Kumar Gupta, SEBI Registered Research Analyst, INH000020226, Vijay Gupta Advisory. SEBI registration and NISM certification do not guarantee performance or assure returns. Securities markets are subject to market risks. No holdings in the subject company.
#EquityResearch#USMarket#PsychologyofMoney#MacroViews#Miscellaneous

 Equity Research
 Fundamental Views
 Hidden Gems
 Index Strategies
 International Market
 IPO
 Macro Views
 Miscellaneous
 Personal Finance
 Post-Closing Commentary
 Pre-Opening Commentary
 Psychology of Money
 Sector Breakout
 Stock In News
 Technical Views
 Time To Exit
 Today's Trading Setup
 Trending Sectors
 US Market
 Watch Out For