‹ All Posts
VIJAY KUMAR GUPTA

3 mins ago · SEBI Registration INH000020226

Wipro Q1 PAT flat YoY; margins crumble 120bp
WIPRO
WIPRO
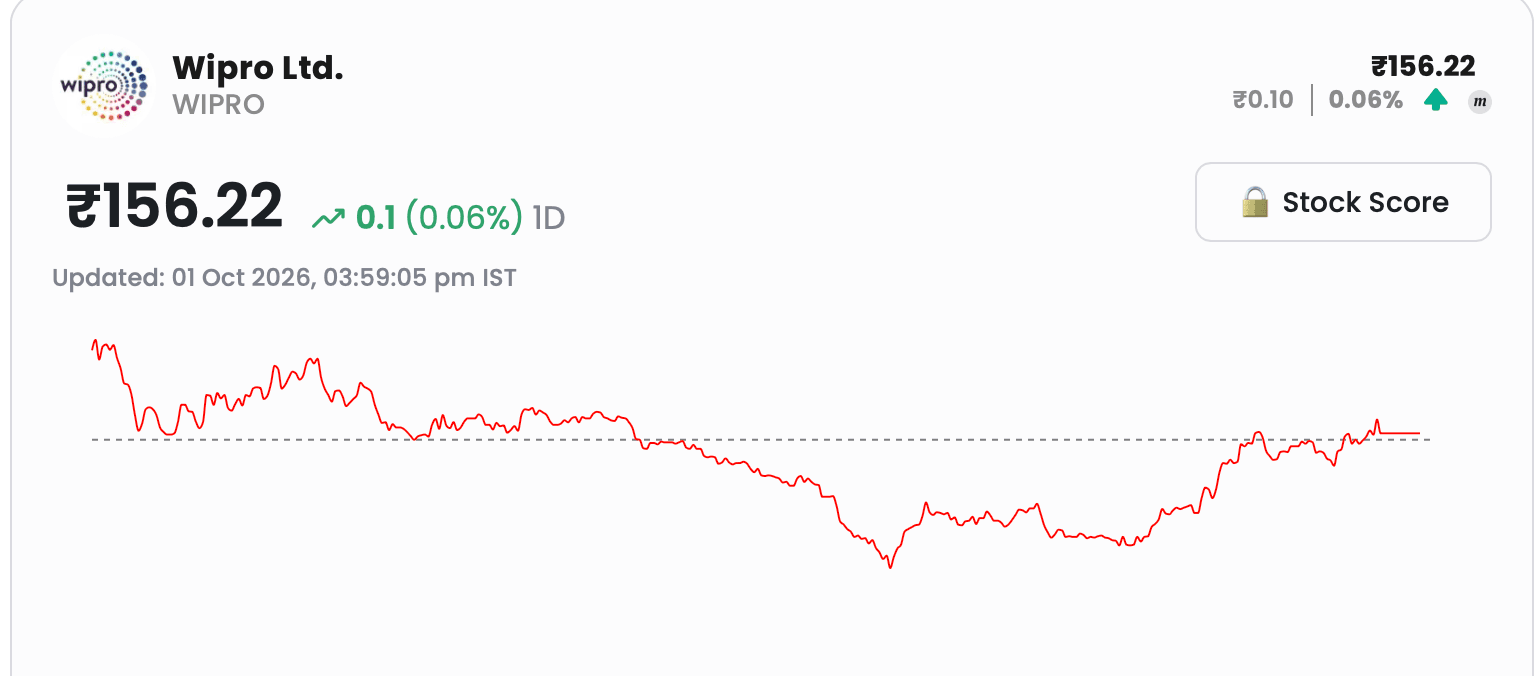
***** BODY: Q1 FY27 (ended 30 Jun 2026): Revenue $2,614.5M (+1.0% YoY, -1.4% QoQ in rupee terms); PAT Rs 33.6Cr (up 0.6% YoY, -4.7% QoQ); EPS Rs 3.20 (up 0.6% YoY, -4.2% QoQ). IT Services operating margin 16.0%, down 1.2pp YoY and 1.3pp QoQ. Large deal bookings accelerated 12.9% QoQ to $1,626M, signaling pipeline strength, but revenue conversion remains sluggish. Margin compression is the red flag. Q4 FY26 margin was 17.3%; Q1 at 16.0% marks a 130bp slide in two quarters. Sequential PAT fell despite flat revenue, proving cost inflation outpaces pricing. Attrition at 13.8% (TTM) is dragging bench utilization and salary costs. Rupee depreciation masked underlying growth; guidance pegged Q1 at $2,597–$2,651M; actual $2,614.5M landed mid-range. Stock: Rs 156.22 (01 Oct), down 35.2% YoY and 13.0% past month. Exited Nifty 50 on 30 Sep. P/E 12.21 looks cheap, but dividend yield 5.87% is the sole comfort. 52-week range Rs 154–Rs 271 shows severe re-rating risk. Hold awaiting attrition stabilization and cost control evidence. Q2 FY27 (Oct 15) is the critical read. Rs 2 interim dividend cushions downside; not a fresh entry until margin recovery plan emerges. Rs 150Cr buyback at Rs 250/share pending approval—accretive only if EBITDA holds. Vijay Gupta Advisory (SEBI RA INH000020226) — This is data and analysis, not a recommendation. See disclosures at *****

#WatchOutFor#MacroViews#SectorBreakouts#HiddenGems#TrendingSectors
WIPRO_DIALY_UPDATES.png